Unpacking the 2027 National Budget: Major Tax highlights and what they mean for Zimbabwe
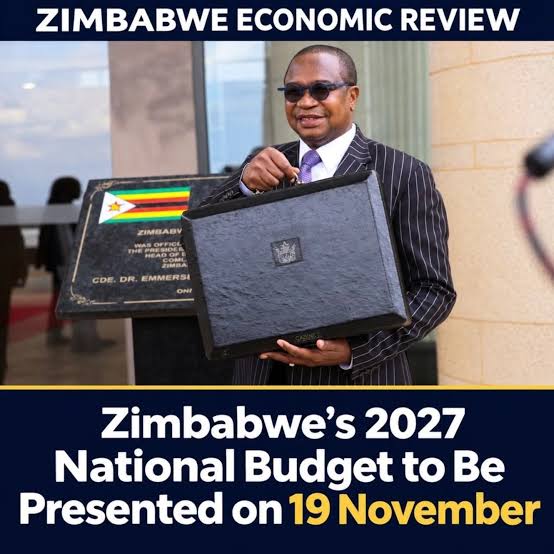
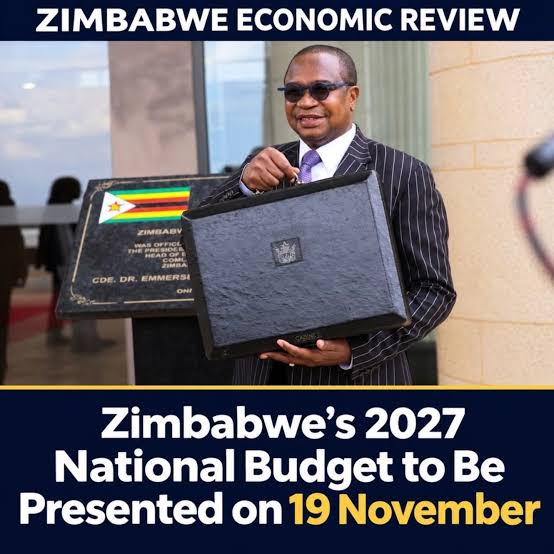
On 19 November 2026, the Minister of Finance, Economic Development and Investment Promotion, Hon. Prof. Mthuli Ncube, presented Zimbabwe’s 2027 National Budget under the theme “Accelerating Economic Transformation and Building Resilience to Climate and Global Shocks.”
With the country steering toward Vision 2030, Treasury’s fiscal game plan for 2027 walks a tightrope. On one hand, the government needs to raise its revenue-to-GDP ratio from 17.5% to 22% by 2030 without relying on external borrowing. On the other, it must cushion businesses and ordinary citizens against global geopolitical shocks and an anticipated Super El Niño drought.
The major tax changes announced in the 2027 Budget and the Finance Bill, alongside an honest look at who wins, who loses and where the policies might fall short.
Personal Income Tax (PAYE) Relief
The Tax Change
To combat “bracket creep” caused by nominal income adjustments, the tax-free threshold for Personal Income Tax (PAYE) is being raised from US$100 to US$150 (or the ZiG equivalent) per month, effective 1 January 2027. The tax bands have also been adjusted, capping at US$3,000 per month, above which a top marginal tax rate of 40% applies. Additionally, the prescribed interest rate for employer-assisted concessionary loans has been lowered from SOFR + 5% to SOFR + 3.5% (and set at 15% for ZiG loans).
The Impact
- Individuals: Low-income earners get immediate breathing room on their payslips, while middle-income workers benefit from widened tax brackets. Treasury estimates this will put roughly US$81 million back into taxpayers’ pockets.
- Businesses: Employers face slightly lower administrative friction when offering staff loans as welfare perks, and retail businesses should see a mild uptick in consumer spending.
- The Economy: Boosting disposable income helps stimulate aggregate demand, which is crucial for keeping domestic consumption afloat during a projected drought year.
The Benefits vs. The Demise
- The Upside: It improves taxpayer morale, encourages voluntary compliance, and offers genuine relief to struggling households without destabilizing the broader fiscal framework.
- The Flaw (Demise): While a US$50 bump in the tax-free threshold is welcome, it still falls well short of the actual cost of living and the urban poverty datum line in Zimbabwe. For the average worker, the relief will easily be wiped out if El Niño pushes food prices up in 2027.
Reduction of the Intermediated Money Transfer Tax (IMTT)
The Tax Change
Continuing the gradual rollback of the controversial 2% transaction tax, the 2027 Budget trims the IMTT rate on ZiG-denominated electronic transactions from 1.5% to 1.25%, and on foreign currency transactions from 2% to 1.75%. High-value transactions exceeding US$500,000 remain capped at a flat tax of US$10,150. However, businesses can only claim IMTT as a tax-deductible expense if they prove to ZIMRA that their declared quarterly revenues match their formal bank deposits.
The Impact
- Individuals: Everyday digital payments, mobile money transfers, and bank transactions become marginally cheaper, especially when transacting in local currency.
- Businesses: Operating expenses drop slightly for formal companies moving high volumes of money through banks. However, compliance scrutiny is tighter than ever.
- The Economy: Maintaining a 0.5% spread between ZiG and USD transfers reinforces the government’s push for de-dollarisation and encourages businesses to bank their cash rather than operating in the shadows.
The Benefits vs. The Demise
- The Upside: Treasury is sacrificing roughly US$100 million in direct revenue to lower the cost of financial intermediation, which should improve transaction traceability and formalization.
- The Flaw (Demise): Even at 1.25% and 1.75%, IMTT remains a cascading tax on turnover rather than profit. In an economy dominated by an informal cash sector, any tax on formal bank transfers still penalizes compliant businesses and tempts smaller traders to stick strictly to physical USD cash.
Aggressive VAT Compliance and the US$500,000 Surcharge
The Tax Change
To plug massive revenue leakages in sectors like Fast-Moving Consumer Goods (FMCG), hardware/building materials, and motor spares, Treasury has introduced a punitive Minimum VAT Compliance Surcharge of US$500,000 per tax period. This applies to VAT-registered operators who fail to fiscalize or file returns, as well as businesses meeting the compulsory registration threshold that choose to remain unregistered. Treasury is also rolling out a whistleblower reward system for citizens who report non-compliant businesses.
The Impact
- Individuals: Consumers may face fewer “cash-only, no-receipt” scenarios at major retail outlets, though whistleblower incentives could create social friction.
- Businesses: Formal retailers get a fairer playing field against unregistered competitors undercutting them on price. Conversely, medium-sized businesses caught offside on fiscalization face an existential financial threat.
- The Economy: Aims to protect Value Added Tax, which remains Zimbabwe’s single largest revenue generator (accounting for nearly 28% of total collections).
The Benefits vs. The Demise
- The Upside: It creates a massive deterrent against deliberate tax evasion and forces large informal traders into the formal tax net.
- The Flaw (Demise): A flat US$500,000 penalty per tax period—regardless of actual turnover—is wildly disproportionate for smaller or mid-tier enterprises. Instead of formalizing borderline businesses, such a draconian fine risks driving them entirely underground or bankrupting them over administrative delays.
Mining Royalties and Export Taxes on Raw Minerals
The Tax Change
The government is tightening the screws on raw mineral exports while adjusting to global commodity shifts:
- Platinum Group Metals (PGMs): Export tax on unbeneficiated platinum is strictly tiered: 10% on washed ore, 5% on concentrate, 2.5% on matte, and 0% on refined individual PGMs.
- Lithium: Export tax on lithium concentrate will now be calculated based on the gross fair market value of the equivalent lithium sulphate recoverable (using a 6:1 conversion ratio for 5% grade and 5:1 for 6% grade), with no deductions allowed for transport costs. Refined lithium sulphate attracts 0% export tax.
- Gold & Diamonds: The 10% mineral royalty on gold will now apply strictly to the incremental value above US$5,000 per ounce. Meanwhile, to help natural diamond miners survive competition from lab-grown stones, diamond royalties are cut from a flat 10% to 5% for stones valued below US$100 per carat, with 10% applying only to the incremental value above US$100.
The Impact
- Businesses: Mining houses exporting raw concentrates (especially lithium and PGM producers) face squeezed margins and higher tax bills, while those investing in local refineries get tax immunity. Gold and diamond miners receive vital market-aligned relief.
- The Economy: Forces structural transformation by keeping mineral value addition, jobs, and downstream industries inside Zimbabwe.
The Benefits vs. The Demise
- The Upside: Stops transfer pricing and under-declaration of mineral grades at the border, ensuring Zimbabwe captures fair value from its finite resources.
- The Flaw (Demise): Penalizing miners before the country has sufficient, cheap, and reliable baseload electricity to run energy-intensive smelters and refineries puts the cart before the horse. High export taxes during a projected 2027 dip in global mineral prices could stall capital expansion.
Digital Economy Taxation and the “e-TRACE” System
The Tax Change
Zimbabwe is formally bringing the digital age into the tax net. Financial institutions will withhold Digital Services Withholding Tax (DSWT) on offshore platforms (streaming, cloud computing, e-hailing, online marketplaces and betting), and these services will be exempt from double-taxation via import VAT. ZIMRA is also procuring a new automated system called e-TRACE to monitor electronic transactions, while Virtual Asset Service Providers (crypto exchanges/platforms) are now formally recognized under financial services tax laws. Additionally, Capital Gains Tax (CGT) is being introduced on the disposal of virtual assets.
The Impact
- Individuals: Subscriptions to foreign streaming platforms, cloud storage, and digital apps will consistently reflect local tax deductions, and crypto traders must now account for Capital Gains Tax.
- Businesses: Local tech startups and digital platforms face clearer rules, while foreign tech giants can no longer extract revenue from Zimbabwean users without contributing to the fiscus.
- The Economy: Modernizes Zimbabwe’s tax architecture to match global standards and captures revenue from a rapidly digitizing economy.
The Benefits vs. The Demise
- The Upside: Levels the playing field between brick-and-mortar local businesses and offshore digital providers, while bringing clarity to the fast-growing virtual asset space.
- The Flaw (Demise): Enforcing CGT on decentralized virtual assets (like peer-to-peer crypto trades) is notoriously difficult. Furthermore, taxing imported digital services and cloud infrastructure ultimately raises the cost of doing business for local tech startups and SMEs that rely on foreign software tools.
Customs Duty Cuts on Tech, Green Transport and Industrial Inputs
The Tax Change
To curb smuggling and boost local assembly, Treasury has slashed several import duties:
- Mobile Phones & ATMs: Customs duty drops from 25% to 0% on cell phones and ATMs.
- Electric Vehicles (EVs): Duty on EVs and charging infrastructure drops from 25% to 10%.
- Motor Assembly & Fertiliser: Complete suspension of duty (0%) on Semi-Knocked Down (SKD) kits for local assemblers of motorcycles, trucks, EVs, and trailers, alongside duty rebates on raw materials for local fertiliser manufacturers.
- Assistive Devices & Basic Goods: Duty removed entirely on wheelchairs, hearing aids, white canes, and Braille watches, while freshwater fish is now exempt from VAT.
The Impact
- Individuals: Smartphones, assistive medical devices, and basic protein (fish) become more affordable through formal retail channels.
- Businesses: Formal cellphone retailers can finally compete with briefcase smugglers. Local vehicle assemblers and fertiliser plants get cheaper inputs to ramp up production.
- The Economy: Promotes green energy adoption, supports domestic industrialization ahead of AfCFTA trade integration, and shifts tax collection from punitive border tariffs to domestic consumption taxes (VAT).
The Benefits vs. The Demise
- The Upside: Smart policy that recognizes high tariffs only fuel smuggling. Removing duty on phones and EVs stimulates formal retail growth and environmental sustainability.
- The Flaw (Demise): For fertiliser manufacturers and vehicle assemblers, tax rebates alone won’t guarantee lower consumer prices if domestic production remains hampered by high power tariffs, aging machinery, and high local borrowing costs.
Property, Trusts and Used Car Valuation Overhauls
The Tax Change
- Capital Gains Tax (CGT) & Trusts: Transferring property between trusts to change beneficial ownership will now attract CGT (excluding REITs), closing a popular tax-avoidance loophole. Conversely, CGT is scrapped entirely on marketable securities listed on the Zimbabwe Stock Exchange (ZSE) to boost capital market activity.
- Used Motor Vehicles: ZIMRA is scrapping the invoice-based valuation system (which was rife with under-invoicing) in favor of an Automated Motor Vehicle Valuation Framework based strictly on vehicle class, model, engine capacity, and year of manufacture, regardless of physical condition. Only accredited clearing agents or the actual owners can clear vehicles.
The Impact
- Individuals: Buying and selling shares on the ZSE becomes much more attractive. However, everyday citizens importing older, slightly damaged second-hand cars can no longer use lower purchase invoices to pay less duty.
- Businesses: Real estate investors face a progressive Stamp Duty scale (ranging from 1% up to 7.5% for properties over US$300,000), while unregistered “runners” at border posts are effectively outlawed.
The Benefits vs. The Demise
- The Upside: Eliminates corruption and arbitrary duty assessments at border posts while breathing much-needed liquidity back into the ZSE.
- The Flaw (Demise): Valuing imported used cars strictly by model and year—ignoring accident damage or high mileage—penalizes low-income buyers importing cheaper, high-mileage vehicles, effectively raising the barrier to car ownership for working-class Zimbabweans.
Verdict
The 2027 National Budget shows a Treasury that is increasingly sophisticated in plugging loopholes, digitizing tax administration, and encouraging local value addition. By cutting IMTT, scrapping ZSE Capital Gains Tax, and removing duty on phones and industrial inputs, Prof. Mthuli Ncube has offered genuine olive branches to the formal sector.
However, the heavy reliance on punitive compliance measures—such as the US$500,000 VAT surcharge and strict border valuations—risks squeezing the very businesses struggling to survive in a high-cost, drought-threatened economy. Ultimately, the success of these tax reforms in 2027 will depend on whether ZIMRA applies them fairly without suffocating small enterprises into the informal sector.