Navigating the Festive Gap: What October’s ZiG Inflation Rise Means for Civil Servants and Retailers
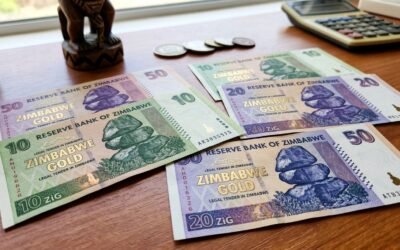
As Zimbabwe approaches the traditional year-end spending boom, fresh economic data presents a mixed signal for consumers, business owners, and policymakers alike. Annual inflation tied to the Zimbabwe Gold (ZiG) accelerated to 4.3% in October 2026, up from 3.7% in September and a low of 2.9% in August. Contrastingly, annual US-dollar (USD) inflation eased slightly to 3.2% from 3.5%, leaving the local currency’s inflation rate 1.1 percentage points above its foreign counterpart.
While these figures remain dramatically lower than historical hyperinflationary surges, the widening spread between the dual currencies raises essential questions about the durability of Zimbabwe’s monetary stabilization program as the November bonus season arrives.
Why Did ZiG Inflation Creep Up?
The underlying dynamics behind the October upturn reflect localized cost pressures rather than systemic monetary collapse:
- Rising Transport and Distribution Costs: The primary catalyst behind October’s increase was higher domestic transport pricing. Logistics, fuel fluctuations and transit costs disproportionately impact local-currency pricing structures due to local fuel and toll adjustments.
- Domestic vs. Imported Dynamics: Because US-dollar inflation cooled to 3.2%, the latest inflationary uptick is not uniformly distributed. Imported goods priced in hard currency experienced relative price stability, whereas service fees, local transit, and domestic supply chains priced in ZiG bore the brunt of price realignments.
- Uneven Trajectory in 2026: The October figures continue a pattern of fluctuation throughout the year. ZiG inflation started 2026 at 4.1%, peaked at 4.8% in April driven by early-year fuel costs, dropped to a trough of 2.9% in August, and has now reversed course for two consecutive months.
Is This Good News for Civil Servants ahead of the November Bonus?
For Zimbabwe’s extensive civil service, the upcoming November bonus month is a vital lifeline. Evaluating whether current conditions are favorable depends on how bonuses are disbursed and spent:
The Positive Side
- Macroeconomic Stability: Compared to December 2025 when ZiG inflation stood at an uncomfortable 15% the current single-digit environment (4.3%) means purchasing power is far more predictable than in previous years.
- Blended Bonus Packages: If bonus payments maintain a significant USD component alongside ZiG, workers benefit directly from the easing USD inflation rate (3.2%).
The Challenges
- Local Currency Erosion: The 1.1 percentage point gap between ZiG and USD inflation signals that funds held or paid strictly in ZiG lose real value faster than those in hard currency. If bonus payouts contain substantial local currency portions, civil servants may rush to convert or spend them quickly before local prices adjust upward further during peak holiday demand.
- Transport Strain: Because transit costs led the October inflation rise, commuting workers face immediate, non-discretionary pressure on their daily budgets.
Verdict for Civil Servants: The environment is substantially better than late 2025, offering genuine relief, but the recent tick upward in ZiG inflation will require careful household budgeting to avoid holiday margin squeeze.
What Does This Mean for Businesses Facing the Festive Season?
The festive period (November through December) typically generates the highest retail turnover of the year. For the business community, the October data delivers a dual narrative:
Opportunities
- Surge in Liquidity: The injection of November bonus funds into the market will drive strong consumer demand across retail, groceries, fast-moving consumer goods (FMCG) and transport.
- Stable USD Pricing: Easing USD inflation gives retailers selling primarily in hard currency room to maintain stable margins without discouraging budget-conscious shoppers.
Operational Risks
- Currency Preferences and Exchange Pressure: The widening gap (4.3% ZiG vs. 3.2% USD) tests the monetary transmission mechanism. Retailers pricing goods under formal exchange-rate guidelines may face margin compression if their wholesale supplier costs in ZiG outpace retail selling caps.
- Inventory Costs: Higher transport costs mean stocking shelves for Christmas will carry elevated freight expenses, which businesses must either absorb or pass on to end consumers.
Long-Term Outlook
The broader achievement of 2026 remains notable. Bringing annual ZiG inflation down from 15% at the end of 2025 to steady single digits demonstrates the efficacy of tighter liquidity management, restrained local-currency growth, and robust foreign-currency inflows.
However, October’s uptick serves as a clear reminder: keeping inflation in single digits does not permanently insulate the economy from imported price shocks, domestic logistics bottlenecks, or currency preference shifts. As liquidity rises in November and December, central monetary authorities will need to keep a firm grip on local currency expansion to ensure that October’s brief uptick does not turn into a broader trend heading into 2027.