The Reserve Bank of Zimbabwe’s 70:30 Forex Retention Policy
Overview.
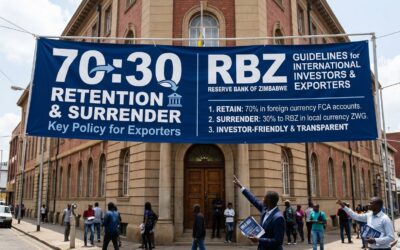
The Reserve Bank of Zimbabwe (RBZ) maintains a foreign exchange retention threshold requiring exporters to surrender 30% of their export earnings in exchange for local currency (Zimbabwe Gold – ZiG) at the official interbank rate, while retaining 70% in foreign currency (US Dollars).
While intended to support official foreign exchange reserves and drive demand for the domestic currency, the policy acts as an implicit surrender tax on export revenues. This report evaluates the policy’s origins, evolution, global comparative contexts, and specific economic consequences for the central bank, national fiscal stability, and private sector viability.
Policy Overview and Operational Framework
Mechanics of the 70:30 Rule
Under the 70:30 retention policy, when an enterprise exports goods or services:
- 70% Retained: Deposited into the exporter’s Foreign Currency Account (FCA) for direct use in foreign supplier payments, capital expenditure, or foreign debt servicing.
- 30% Surrendered: Converted automatically by the RBZ into local currency (ZiG) at the ruling interbank exchange rate and credited to the exporter’s domestic bank account.
Export Revenue: US$100
├── US$70 ──> Retained in FCA (Foreign Currency Account)
└── US$30 ──> Liquidity Surrender to RBZ @ Interbank Rate ──> Paid to Exporter in ZiG
Historical Context and Policy Evolution
Foreign exchange surrender requirements in Zimbabwe have historically fluctuated in response to foreign currency liquidity constraints, currency regimes, and economic cycles.
[2016-2019]                   [2020-2023]                   [2024-Present]
Extreme Liquidity Crisis      Multi-Currency / Post-COVID   Introduction of ZiG
• Retention: 30%-50%          • Retention: 60%-80%          • Retention Standardized at 70:30
• High distortions            • Frequent sector revisions    • RBZ re-affirms de-dollarization goal
- The Export Incentive and Bond Note Era (2016–2019): Initial surrender rules were paired with export incentives. As exchange rate disparities between the nominal USD parity and the informal market widened, surrender requirements functioned increasingly as implicit taxation.
- Multi-Currency Re-introduction and COVID-19 Era (2020–2023): Surrender rates varied dynamically by sector (e.g., gold mining, agriculture, manufacturing). Mining exporters often faced thresholds ranging from 60% to 85%, depending on global commodity prices and domestic foreign currency demand.
- The ZiG Standard (2024–Present): Following the introduction of the structured, asset-backed currency—the Zimbabwe Gold (ZiG)—in April 2024, the RBZ standardized the retention rate at 70:30 across primary export sectors. Despite private sector requests for an increase to 80% or 90%, the RBZ has explicitly maintained the 70:30 allocation as a tool to promote national reliance on local currency.
Comparative Global Context
Foreign exchange surrender regimes are generally employed by developing economies facing capital flight, severe balance-of-payments deficits, or structural exchange rate instability.
| Country | Surrender Threshold | Conversion Rate / Mechanism | Primary Objectives & Outcomes |
| Zimbabwe | 30% | Official Interbank Rate (ZiG) | Reserve build-up, promoting local currency usage; creates cost-revenue mismatch for exporters. |
| Nigeria | Volatile / Sector-Specific | Official Investors & Exporters (I&E) Window | Formerly required high repatriation; liberalised recently to unify parallel and official exchange markets. |
| Argentina | Historical (Multi-tier) | Official Exchange Rate (Cepo Cambiario) | Suppressed export competitiveness; encouraged unofficial trade channels until economic reforms eased controls. |
| Ghana | Sector-specific (e.g., Oil/Mining) | Market-determined Commercial Rates | Surrender requirements fund energy imports; manageable impact due to lower parallel market premiums. |
Key Takeaway: International experience demonstrates that forced retention rules work effectively only when the official conversion rate closely tracks the true market-clearing rate. When a wide gap exists between official and market rates, surrender rules function as export taxes, discouraging formal cross-border trade.
Structural Impact on Government and the RBZ
Advantages and Objectives
- Accumulation of Foreign Reserves: The primary benefit to the RBZ is a guaranteed inflow of hard currency. These funds bolster official international reserves, cover critical sovereign debt obligations, and finance essential national imports (e.g., fuel, grain, medical supplies, electricity).
- Mopping Up Local Currency and Anchoring ZiG Demand: Requiring transactions in ZiG forces local markets to use the domestic unit, creating baseline demand for the currency.
- Monetary Control: Direct control over a third of export proceeds provides the central bank with liquidity to intervene in the interbank market when foreign exchange supply is low.
Risks and Structural Challenges
- Creation of Implicit Fiscal Liabilities: Converting foreign currency at official rates can distort central bank balance sheets if domestic currency valuations adjust rapidly, increasing operational expenses.
- Export Sector Contraction: If the surrender requirement discourages investment in primary export industries (such as mining and commercial agriculture), overall national export volume declines—reducing total foreign currency inflows over the long term.
Microeconomic Impact on Exporting Businesses
OPERATIONAL MISMATCH FOR EXPORTERS

Revenue Structure:                   Cost Structure:
┌─────────────────────────┐          ┌─────────────────────────┐
│ 70% US Dollars          │          │ ~80% - 95% US Dollars   │
│ 30% Local Currency (ZiG)│          │ (Fuel, Spares, Power)   │
└─────────────────────────┘          └─────────────────────────┘
            │                                    │
            └───────────────┬────────────────────┘
                            ▼
              Margin Squeeze & Disincentive
1. Cost-Revenue Mismatch and “Implicit Tax” Effect
- Dollarized Cost Structures: Exporters in Zimbabwe incur the majority of their inputs in foreign currency including electricity tariffs, imported machinery, fuel, specialized logistics, and foreign capital servicing.
- Effective Margin Loss: When 30% of revenue is converted to local currency at official interbank rates while key input suppliers demand hard currency or adjust prices to parallel market rates, the business absorbs a direct margin loss. Exporters view this operational difference as an additional tax on gross top-line revenue.
2. Disincentive to Expand Capital Investment
- In capital-intensive industries such as mining, long-term project viability relies on clear, predictable cash flows in stable currencies. The risk of exchange rate slippage on the surrendered 30% increases the cost of capital and raises hurdle rates for international investors.
3. Supply Chain Disruption and Informal Re-routing
- To manage liquidity constraints created by local currency holdings, firms may seek domestic suppliers willing to accept ZiG. If local supply chains cannot meet quality or volume needs, businesses may delay expansion plans or explore alternative corporate structures to minimize direct exposure.
Strategic Recommendations
For the Reserve Bank of Zimbabwe (RBZ)
- Narrow Market Discrepancies: Ensure the interbank market operates dynamically to prevent significant divergence between official and market exchange rates, minimizing the effective implicit tax on exporters.
- Gradual Escalation Trajectories: Introduce flexible surrender thresholds pegged to verified foreign input ratios. High-input exporters could be granted higher retention allowances (e.g., 80:20) to safeguard operational viability.
- Allow ZiG Tax Payment Offsets: Enable exporters to settle all direct state obligations—including mining royalties, corporate income tax, and municipal tariffs—in the local currency received via surrender.
For Exporting Enterprises
- Supply Chain Localisation: Identify domestic input options where settlement in ZiG is standard, matching local currency inflows with corresponding liabilities.
- Treasury Management: Optimize cash flow timing by utilizing local currency proceeds for immediate, predictable domestic obligations (such as local payroll, local taxes, and domestic services) to minimize currency holding risks.
- Value-Addition Strategies: Move up the supply chain into processed or semi-processed goods to capture higher gross margins, diluting the net impact of the 30% surrender requirement.
Conclusion
The RBZ’s adherence to the 70:30 forex retention threshold highlights the central bank’s commitment to supporting the ZiG and securing essential foreign exchange reserves. However, sustaining this policy requires balancing monetary stability goals against private sector competitiveness. Ensuring market-driven exchange rates and providing flexible tax settlement mechanisms in local currency will be critical to supporting national export growth.
Key Findings:
The Policy Core:-The policy acts as a dual-purpose monetary tool—providing the RBZ with foreign reserves while driving baseline demand for local currency (ZiG).
Private Sector Mechanics:-Because most exporters face dollarized cost structures (fuel, power, imported capital goods), surrendering 30% at official rates functions as an implicit surrender tax if parallel market premiums exist.
Global Context:-Countries using surrender requirements achieve long-term stability primarily when the official conversion rate matches realistic market-clearing rates.