Navigating Cross-Border Digital Services and Banking Remittances
A Technical and Practical Tax Article.
Walking the Talk.
In the modern digital economy, physical operations and virtual software ecosystems are inextricably linked. For specialized service providers such as Lambacasi Co. a premier, VAT-registered enterprise in Zimbabwe specializing in the precision diagnosis, servicing, and repair of Mercedes-Benz motor vehicles—operational excellence relies heavily on proprietary OEM (Original Equipment Manufacturer) diagnostic software. To maintain diagnostic accuracy, communicate with vehicle control units, and access real-time technical bulletins, Lambacasi Co. must regularly download software updates originating from Germany.
These updates require foreign currency remittances sent via local banking channels, specifically through Stanbic Bank Zimbabwe. When funds leave Zimbabwe to pay a German software vendor, multiple overlapping legal and tax frameworks are triggered under Zimbabwean tax law. These include the Value Added Tax Act [Chapter 23:12], the Income Tax Act [Chapter 23:06], Statutory Instruments governing Digital Services Tax (DST), and Non-Residents’ Tax on Remittances and Royalties.
We dive into a rigorous, in-depth technical breakdown designed in plain, accessible terms for management, outlining the tax heads involved, the statutory compliance obligations, the role of Stanbic Bank as an authorized dealer, and the precise adjustments Lambacasi Co. must implement to remain fully compliant with the Zimbabwe Revenue Authority (ZIMRA).
1. Scenario Explanation -The Lambacasi Co. Operational Model
To understand the tax treatment, we must first map out the operational lifecycle of the transaction:
- The Technical Need: Modern Mercedes-Benz vehicles utilize complex Controller Area Network (CAN) bus systems and encrypted electronic control units (ECUs). Lambacasi Co. utilizes specialized diagnostic hardware running cloud-synced software licensed from Germany.
- The Update Cycle: Periodic updates patch diagnostic algorithms, update vehicle fault codes, and grant authorization codes to scan newer models. Each update requires a digital license key or data payload pushed from German servers.
- The Payment Flow: Lambacasi Co. initiates an international funds transfer (IFT) through its commercial banker, Stanbic Bank Zimbabwe, converting local RTGS/ZiG funds or utilizing foreign currency account (FCA) balances to remit Euros or USD to the German software supplier.
- The Regulatory Intersection: Because this transaction involves a cross-border payment for electronic/software services, it attracts rigorous scrutiny under exchange control regulations and tax legislation. ZIMRA views this as an import of services, a digital service, and potentially a royalty or fee subject to withholding taxes.
2. Tax Head 1: Value Added Tax (VAT) on Imported Services
2.1 Statutory Foundation
Under Section 7(1)(a) of the Value Added Tax Act [Chapter 23:12], VAT is levied on the supply of any goods or services imported into Zimbabwe by any person. Furthermore, Section 10(1) defines an “imported service” as a supply of services that is made by a supplier who is resident or carries on business outside Zimbabwe, where the recipient of the supply is resident in Zimbabwe, and the services are utilized or consumed in Zimbabwe for other than making exempt supplies.
2.2 Application to Lambacasi Co.
Because Lambacasi Co. is a VAT-registered operator utilizing the software diagnostic updates within its Zimbabwean workshop to service vehicles (a taxable commercial enterprise), the acquisition constitutes an imported service.
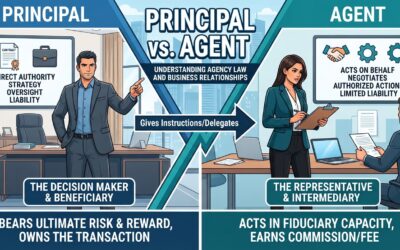
- The Reverse Charge Mechanism: Since the German vendor is not registered for VAT in Zimbabwe and has no physical branch or fiscal representative locally, they cannot charge Zimbabwean VAT. Instead, the burden shifts to Lambacasi Co. via the “reverse charge” mechanism.
- Accounting Requirement: Lambacasi Co. must self-account for output VAT on the imported service in its standard ZIMRA VAT return for the relevant tax period.
- Input VAT Claim: Concurrently, because the software is directly used to carry on its taxable business enterprise (repairing vehicles), Lambacasi Co. can claim an equivalent amount as input VAT, resulting in a net-nil cash flow impact if accounted for correctly, though the declaration is strictly mandatory to avoid severe penalties and interest for non-disclosure.
3. Tax Head 2: Income Tax and the Source Rules
3.1 Statutory Foundation
Under the Income Tax Act [Chapter 23:06], taxation is primarily source-based. Section 8(1) defines gross income to include amounts received or accrued from a source within or deemed to be within Zimbabwe. For intellectual property, software licenses, and cross-border commercial agreements, specific source rules apply under Section 12(4) and Section 12(6)/(7).
3.2 The “Right of Use” and Software Licences
When Lambacasi Co. pays for software updates, is it buying a commodity (goods) or a license to use intellectual property (services/royalties)?
- Under ZIMRA practice and international tax norms, standard off-the-shelf software updates that grant permission to use copyrighted code fall under royalties or know-how payments if they convey the right to use industrial, commercial, or scientific equipment or intellectual property.
- Section 12(4)(a) of the Income Tax Act deems amounts to have accrued from a source within Zimbabwe if received by virtue of the use in Zimbabwe or the grant of permission to use in Zimbabwe any copyright, patent, design, secret process, or similar property.
4. Tax Head 3: Non-Residents’ Tax on Remittances & Royalties
4.1 Statutory Foundation
When a Zimbabwean resident remits funds offshore for royalties, rentals, or technical/management fees to a non-resident entity, Non-Residents’ Tax on Royalties or Non-Residents’ Tax on Fees is triggered under Sections 30 to 35 of the Income Tax Act.
4.2 Application to the German Software Vendor
- Withholding Obligation: Stanbic Bank, acting as an Authorized Dealer under Reserve Bank of Zimbabwe (RBZ) exchange control directives, cannot process the outward remittance without proof of tax clearance or evidence that withholding tax has been accounted for.
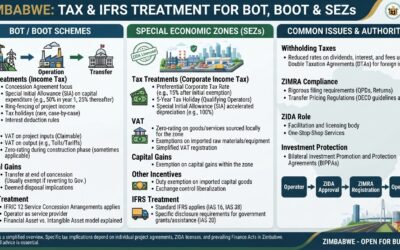
- The Rate: Depending on whether the software payment is classified as a royalty (licensing of copyrighted code) or a service fee, withholding tax rates can range up to 15% (or as modified by any applicable Double Taxation Agreement, though Germany-Zimbabwe DTA provisions require careful administrative substantiation via ZIMRA tax relief certificates).
- The Burden of Proof: The tax is legally a liability of the non-resident German vendor, but Lambacasi Co. (the local remitting entity) is statutory agent appointed to withhold the tax from the gross remittance and pay it over to ZIMRA within the prescribed statutory timeframe (typically within 30 days of withholding).
5. Tax Head 4: Digital Services Tax (DST)
5.1 Statutory Foundation
Zimbabwe introduced legal frameworks via amendments and Statutory Instruments (such as SI provisions governing electronic commerce operators and digital platforms) to capture revenues generated by foreign digital service providers delivering services to persons resident in Zimbabwe.
5.2 Intersection with Traditional Withholding vs. Digital Tax
- The Evolution of E-Commerce Taxation: Section 12A of the Income Tax Act targets electronic commerce operators and cross-border digital service providers. While Digital Services Tax is principally designed to be levied directly on foreign tech giants (e.g., streaming platforms, cloud hosting, global SaaS vendors) generating revenue from Zimbabwean consumers or businesses, the operational enforcement often cascades down to banking channels.
- Bank-Level Scrutiny: Stanbic Bank, as the financial intermediary, is mandated to inspect cross-border payments for software-as-a-service (SaaS), cloud subscriptions, and digital licenses to ensure that neither DST nor digital transaction levies are being bypassed. If the German vendor is classified as an electronic commerce operator supplying digital services into Zimbabwe, ZIMRA monitors whether the provider has registered under simplified tax registration frameworks or if local withholding mechanisms apply.
6. The Mechanics of Bank Processing via Stanbic Bank Zimbabwe
As Lambacasi Co.’s banking partner, Stanbic Bank operates under strict dual mandates: Exchange Control Regulations (enforced on behalf of the RBZ) and Revenue Collection Assistance (cooperating with ZIMRA).
6.1 Documentation Required by Stanbic Bank
To execute the wire transfer to Germany, Stanbic Bank’s Trade Services or Forex Operations department will routinely demand:
- Commercial Invoice / Proforma Invoice from the German software provider detailing the exact nature of the software update or subscription.
- Software License Agreement / End User License Agreement (EULA) to determine if the transaction is a pure product purchase, a service, or a royalty-bearing license.
- Tax Clearance Certificate (ITF 263) or a ZIMRA Withholding Tax exemption/confirmation receipt proving that tax obligations have been satisfied or accounted for.
- Form CD1 or Exchange Control Declaration Forms depending on the threshold and nature of the invisible service payment.
6.2 The Risk of Bank-Imposed Withholding
If Lambacasi Co. presents an invoice for software subscriptions without accompanying ZIMRA tax clearance or proof of self-accounting for withholding tax/VAT, Stanbic Bank is legally restricted from remitting the full gross amount. The bank will either:
- Refuse the transaction until tax compliance is proven; or
- Deduct the statutory withholding tax directly at source from the remitted funds on behalf of ZIMRA.
7. Required Adjustments and Compliance Action Plan for Lambacasi Co.
To avoid transaction delays, bank rejections, and punitive ZIMRA audits, Lambacasi Co. must execute the following structured adjustments:
7.1 Contractual and Invoicing Adjustments
- Review Vendor Invoices: Ensure the German vendor itemizes whether the invoice is for a physical diagnostic tool component, a standalone software update, or an ongoing cloud subscription. Clear categorization prevents ZIMRA from misclassifying standard purchases as high-rate royalties.
- Gross-Up vs. Net-of-Tax Clauses: Review contracts to determine who bears the withholding tax burden. If the German vendor demands a net amount of EUR 1,000, Lambacasi Co. must “gross up” the calculation to ensure the correct withholding tax is remitted to ZIMRA in addition to the net wire transfer, or negotiate that the tax is deducted from the remittance.
7.2 Tax Accounting and Return Adjustments
- VAT Reverse Charge Integration: Configure Lambacasi Co.’s internal accounting system (e.g., Pastel, Sage, or SAP) to automatically record Output VAT and Input VAT on imported services concurrently upon invoice processing, ensuring audit trails match bank statements.
- Withholding Tax Remittance Schedule: Maintain a dedicated ZIMRA Self-Assessment and Withholding Tax ledger. For every foreign software payment processed through Stanbic Bank, calculate the 15% (or applicable DTA rate) withholding tax, file the remittance form through the ZIMRA online portal, and obtain the official ZIMRA receipt.
7.3 Banking and Compliance Protocol with Stanbic Bank
- Pre-Clearance Relationship: Establish a dedicated compliance checklist with Stanbic Bank’s trade finance desk. Present the tax clearance and withholding calculations prior to instruction submission to ensure seamless same-day processing of foreign currency transfers to Germany.
- Digital Tax Monitoring: Keep abreast of ZIMRA public notices regarding Digital Services Tax (DST). If the German provider falls under a registered portal with ZIMRA, obtain their local tax registration number to exempt local withholding where applicable under double-taxation relief rules.
8. Conclusion
For Lambacasi Co., keeping Mercedes-Benz vehicles running at peak performance requires seamless software connectivity with Germany. However, this technical necessity brings complex cross-border tax compliance obligations. By mastering the interaction between VAT on Imported Services, Income Tax source rules, Non-Residents’ Withholding Tax, and Digital Service oversight, Lambacasi Co. can transform potential regulatory landmines into a streamlined, automated compliance workflow. Partnering transparently with Stanbic Bank while maintaining rigorous internal tax accounting adjustments ensures that workshop operations remain uninterrupted, legally secure, and fully aligned with Zimbabwean fiscal laws.