Navigating the Spotlight: An analysis of Withholding Tax on Non-Resident Artistes and Entertainers in Zimbabwe.
1. Are You in the Business of Entertainment?
The modern entertainment industry is borderless. From international music sensations headlining stadium tours in Harare to visiting theater troupes, stand-up comedians, and film production crews, cross-border performances represent a vibrant, high-stakes segment of the global economy. Yet, beneath the glamour of flashing lights, sold-out arenas, and roaring crowds lies a complex, highly regulated fiscal landscape.
If you are a promoter, booking agent, venue owner, manager, or an entertainer operating internationally, you are firmly in a business where tax compliance is non-negotiable. Tax authorities worldwide and notably the Zimbabwe Revenue Authority (ZIMRA) exercise rigorous oversight over income generated within their jurisdictions by visiting talent. Understanding the statutory frameworks, filing obligations, and compliance mechanisms governing non-resident artistes is essential to avoiding severe financial penalties, operational shutdowns, or legal disputes.
This article provides an in-depth examination of the Return for the Remittance of Withholding Tax on Non-Resident Artistes and Entertainers, the legislative architecture anchoring this tax head, and critical judicial precedents shaping tax administration in Zimbabwe.
2. Legislative Architecture Governing the Tax Head
To understand how non-resident artistes are taxed in Zimbabwe, one must navigate a synthesis of the Income Tax Act [Chapter 23:06], the Finance Act [Chapter 23:04], and relevant statutory instruments.
The Statutory Foundation
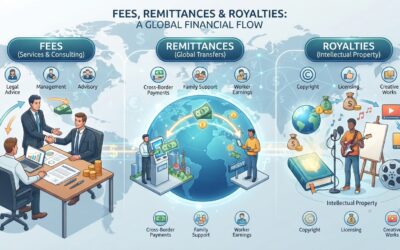
Under Zimbabwean tax law, gross income includes any amount received or accrued from any source within or deemed to be within the country. For non-resident individuals, public entertainers, actors, musicians, athletes, and stage performers who visit Zimbabwe to stage commercial events, films, or broadcasts, the income derived from these activities is subject to specialized withholding mechanisms.
The specific provisions target payments made to non-resident persons who perform services in the fields of theater, music, film, radio, television, or sports. Because non-resident artistes often perform brief engagements and leave the jurisdiction before an annual income tax assessment can be concluded, the legislature instituted a final withholding tax mechanism. This ensures that tax is collected at the source before performance proceeds are externalized.
Rates and Financial Compliance
In terms of the Finance Act [Chapter 23:04] (read alongside the Income Tax Act), non-residents’ tax on fees and remittances applies to specific service categories. For non-resident artistes and entertainers, withholding tax operates as a secured mechanism to capture tax obligations.
- The Currency Imperative: As mandated by section 4A of the Finance Act, where transactions or gross receipts are denominated in foreign currency (such as United States Dollars), the tax must be calculated, accounted for, and remitted in that same foreign currency.
- The Remittance Window: Payors (such as local promoters or event organizers) act as agents for the Commissioner-General. They hold a statutory obligation to withhold the requisite percentage from the gross fee payable to the non-resident artiste and remit the same to ZIMRA within the stipulated statutory deadlines.
3. The Return for the Remittance of Withholding Tax
Compliance under this tax head requires meticulous administrative workflows centering on the completion and submission of the official withholding tax return.
Mechanics of the Return
When a local promoter contracts a foreign artist, the promoter cannot simply pay the gross contractual fee. The compliance lifecycle involves:
- Calculation of Gross Remuneration: Determining the total contractual fee, inclusive of appearance fees, guaranteed minimums, and shared gate receipts allocated to the artist.
- Deduction of Tax: Applying the prescribed withholding tax rate to the gross amount.
- Filing the Return: Completing the designated withholding tax return form, which captures:
- Full particulars of the non-resident artiste or entertainer (name, passport details, foreign tax residency/address).
- Details of the local promoter or withholding agent (Business Partner Number, tax clearance status).
- Nature and location of the event, performance, or production.
- Gross amount paid or credited, the tax withheld, and the net amount remitted.
- Foreign Currency Accounting: In alignment with modern fiscal rules, if the artiste is paid in USD, the return must reflect USD values, and payments must be cleared via approved banking channels into the designated ZIMRA foreign currency accounts.
Obligations and Liabilities of the Withholding Agent
The local promoter or agent bears primary legal liability for the tax. If a promoter fails to withhold the tax, or withholds it but fails to file the return and remit the funds to ZIMRA within the statutory timeframe:
- The promoter becomes personally liable for the unwithheld tax amount.
- Severe penalty interest applies under section 71 of the Income Tax Act (calculated at punitive rates for foreign currency obligations, such as 15% per annum or higher depending on statutory amendments).
- The promoter may face administrative audits and restricted access to tax clearance certificates (ITF 263).
4. Landmark Tax Cases and Judicial Interpretation
Tax legislation does not operate in a vacuum. Over recent years, Zimbabwean courts have robustly interrogated the boundaries of ministerial powers, currency regulations, and administrative fairness, setting vital precedents that impact corporate and entertainment taxpayers alike.
1. M. Mlilo v Minister of Finance (19-HH-605) & Subsequent Validation Acts
This landmark High Court decision underscored the limits of executive rulemaking power. The court declared Statutory Instrument 205/2018 (and its associated amendments to Section 22G) ultra vires the enabling statute, emphasizing that the Minister of Finance cannot legislate outside the strict confines of parliamentary delegation.
- Significance for Taxpayers: This case highlights the perpetual tension between executive statutory instruments and primary parliamentary enactments. While Parliament frequently utilizes retroactive validation acts (such as Act 1 of 2019 and Act 13 of 2019) to cure administrative overreaches, taxpayers retain the right to challenge arbitrary or unconstitutional fiscal levies.
2. Gonese I v Minister of Finance and Economic Development (22-HH-265)
Reinforcing the doctrine of separation of powers, the court in Gonese scrutinized executive amendments to tax provisions (specifically touching on carbon tax and regulatory fees), reaffirming that substantive taxation law must originate from Parliament, not executive decree.
- Significance for Taxpayers: For organizers dealing with non-resident levies and presumptive charges, this line of jurisprudence serves as a reminder that administrative directives or unratified statutory instruments issued by revenue authorities must be rigorously scrutinized against primary legislation.
3. Corporate Foreign Currency and Remittance Rulings (Unki Mines v ZIMRA 22-HH-729; Delta Corporation v ZIMRA 24-SC-062)
In major commercial disputes such as Unki Mines and Delta Corporation, the courts and Supreme Court have grappled with the complex realities of multi-currency accounting, tax payment modalities, and statutory interpretation regarding foreign currency obligations under section 4A of the Finance Act.
- Significance for Taxpayers: The judiciary has consistently upheld that where statutes mandate foreign currency tax compliance, taxpayers must strictly comply with the designated accounting units. However, arbitrary re-interpretations of historical balances by tax authorities without clear statutory backing are subject to judicial correction. Promoters paying foreign artistes must ensure their documentation strictly aligns with these judicial standards to withstand ZIMRA scrutiny.
5. Strategic Best Practices for Event Promoters and Artistes
To ensure seamless operations, international tours, and flawless tax compliance, stakeholders should implement the following checklist:
- Contractual Gross-Up Clauses: Clearly define tax liabilities in performance contracts. Specify whether the agreed fee is gross or net of Zimbabwean withholding tax to avoid last-minute disputes over who bears the tax burden.
- Early Registration: Ensure that both local promoters and foreign artistes (via local representatives) are properly registered with ZIMRA and hold active Business Partner profiles.
- Timely Remittance: File the withholding tax return and remit funds within the statutory deadlines to prevent the accrual of compound interest and penalties.
- Robust Record Keeping: Maintain meticulous records of all cross-border wire transfers, ticketing receipts, and immigration permits (such as temporary employment permits issued under the Immigration Act).
6. Conclusion
The business of entertainment is exhilarating, but compliance failures can turn a successful tour into a fiscal nightmare. By mastering the statutory requirements of the Finance Act [Chapter 23:04] and the Income Tax Act, adhering strictly to the Return for the Remittance of Withholding Tax, and staying attuned to judicial developments, promoters and artistes can secure their operations and ensure that the spotlight remains squarely on their creative excellence.