Navigating Fiscal Compliance and Cross-Border Investment
A Comprehensive Legal and Economic Analysis of Double Taxation Agreements (DTAs), Withholding Taxes on Fees, Remittances, and Royalties in Zimbabwe
1. The Architecture of International Tax Coordination and Source-Based Taxation
The modern global economy operates through relentless cross-border flows of capital, technical expertise, intellectual property, and managerial talent. For emerging and developing economies such as Zimbabwe, integrating into this international commercial grid requires a delicate balance between safeguarding domestic revenue mobilization and offering a competitive, predictable fiscal environment to foreign investors. At the heart of Zimbabwe’s domestic resource mobilization strategy lies the anchor principle of source-based taxation, enshrined primarily within the Income Tax Act [Chapter 23:06] and regulated through the charging provisions of the Finance Act [Chapter 23:04]. Under this statutory framework, income derived from or deemed to be from a source within Zimbabwe is subject to tax, regardless of the residence of the recipient.
However, unmitigated source-based taxation applied unilaterally across multiple jurisdictions inevitably generates friction, most notably in the form of international juridical double taxation—where the same taxpayer is taxed on the same income in both the state of source and the state of residence. Such fiscal overlap creates an intolerable economic burden that stifles foreign direct investment (FDI), discourages technology transfers, and encourages aggressive tax planning or capital flight. To mitigate these distortions, states establish bilateral networks of Double Taxation Agreements (DTAs)—international treaties modeled predominantly on the Organisation for Economic Co-operation and Development (OECD) Model Tax Convention and the United Nations (UN) Model Double Taxation Convention between Developed and Developing Countries.
In Zimbabwe, DTAs operate as supreme instruments of international law that interact dynamically with domestic statutes. When a foreign entity provides technical services, transfers management know-how, remits branch profits, or licenses intellectual property to a Zimbabwean resident, the interaction between domestic withholding taxes (specifically non-residents’ tax on fees under Section 30, remittances under Section 31, and royalties under Section 32 of the Income Tax Act) and applicable DTA provisions determines the final tax cost of the transaction. Furthermore, this intricate legal architecture must be navigated alongside foreign currency compliance imperatives under Section 4A of the Finance Act [Chapter 23:04], shifting monetary regimes, and an increasingly robust body of landmark judicial precedents from Zimbabwean superior courts.
This article provides a rigorous, exhaustive analysis of Double Taxation Agreements in Zimbabwe. It explores their definition, legal standing, and paramount importance, breaks down specific treaty rates for fees, remittances, and royalties with empirical statutory comparisons, analyzes why foreign and domestic investors must master these instruments, and integrates judicial oversight and currency mandates into a cohesive compliance framework.
2. Conceptualizing Double Taxation Agreements (DTAs): Definition and Legal Status
A. What is a Double Taxation Agreement?
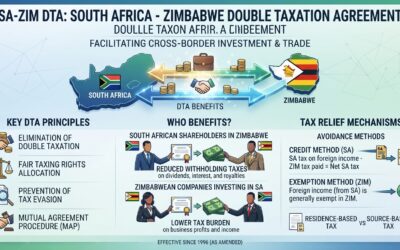
A Double Taxation Agreement (DTA) is a bilateral treaty concluded between two sovereign states for the avoidance of double taxation and the prevention of fiscal evasion with respect to taxes on income and on capital. The fundamental objective of a DTA is to eliminate or mitigate the incidence of international double taxation, thereby promoting economic cooperation, trade, and investment between the contracting states.
To achieve this, a DTA performs several core functions:
- Allocation of Taxing Rights: It establishes binding rules on which of the two contracting states has the primary right to tax specific categories of income (e.g., business profits, dividends, interest, royalties, and technical fees), and which state must cede its domestic taxing rights or provide relief.
- Elimination of Double Taxation: It obligates the residence state to eliminate double taxation through either the Exemption Method (excluding foreign-source income from domestic taxable base) or the Credit Method (allowing a credit for taxes paid in the source state against domestic tax liability).
- Prevention of Fiscal Evasion: It incorporates mechanisms for administrative cooperation, including Exchange of Information (EOI) provisions and Mutual Agreement Procedures (MAP), allowing revenue authorities to combat tax avoidance, base erosion, and profit shifting (BEPS).
- Non-Discrimination: It ensures that nationals and permanent establishments of the partner state are not subjected to more burdensome taxation than domestic nationals and enterprises operating under similar conditions.
B. Legal Standing and Hierarchy of Norms in Zimbabwe
Under Zimbabwean constitutional and administrative law, the domestication and application of international treaties are governed by Section 327 of the Constitution of Zimbabwe, 2013. Unlike monist legal systems where international treaties automatically form part of domestic law upon signature, Zimbabwe adheres to a dualist tradition regarding international agreements.
An international treaty concluded by the executive branch does not have the force of law domestically until it has been approved by Parliament and enacted into domestic law through specific legislative incorporation. For tax treaties, Section 108 of the Income Tax Act [Chapter 23:06] empowers the President (acting through proclamations published in statutory instruments) to declare that arrangements concluded with the government of any country outside Zimbabwe—aimed at affording relief from double taxation—shall have effect in relation to income tax, supertax, or undistributed profits tax as if enacted within the Income Tax Act itself.
The Conflict of Laws Rule: Where a DTA has been duly gazetted and brought into force, it operates as a specialized legal regime. In the event of an irreconcilable conflict between the provisions of the Income Tax Act and an operative DTA, the provisions of the DTA generally prevail over domestic law with respect to the taxes and persons covered by the treaty. This supremacy ensures that foreign investors are granted treaty benefits (such as reduced withholding tax caps) notwithstanding higher baseline rates stipulated in the domestic Finance Act. However, domestic anti-avoidance rules (such as General Anti-Abuse Rules under Section 98 of the Income Tax Act and Transfer Pricing Regulations under Statutory Instrument 109 of 2019) continue to apply to treaty transactions to prevent treaty shopping and artificial arrangements.
3. The Paramount Importance of DTAs for Foreign and Domestic Investors
For international investors evaluating cross-border capital deployment into Zimbabwe, DTAs are not merely esoteric legal texts; they are foundational instruments of financial modeling, risk mitigation, and capital structuring.
A. Mitigation of the Tax Cost Barrier
Without a DTA, cross-border transactions face compounding tax inefficiencies. For instance, a foreign licenser licensing proprietary software to a Zimbabwean corporate client would face a domestic non-residents’ tax on royalties of 15% under Section 32 of the Income Tax Act and Section 21 of the Finance Act. If the licenser’s home country also taxes worldwide income without granting a unilateral tax credit for Zimbabwean taxes withheld, the economic return is severely eroded.
DTAs eliminate this barrier by capping the source-state withholding tax (e.g., reducing royalty withholding from 15% to 10% or 0%) and mandating that the residence state grant a tax credit. This reduction directly enhances the net cash flow of the investment project, improving internal rates of return (IRR) and net present value (NPV) calculations.
B. Legal Certainty and Dispute Resolution
Cross-border taxation is fraught with conflicting jurisdictional interpretations. A payment classified as “management fees” by the Zimbabwe Revenue Authority (ZIMRA) under domestic law might be classified as “business profits” requiring a Permanent Establishment (PE) under a DTA.
DTAs provide investors with legal certainty by defining key concepts (such as “Permanent Establishment,” “Royalties,” and “Independent Personal Services”) using internationally recognized standards. Furthermore, the Mutual Agreement Procedure (MAP) enshrined in Article 25 of standard DTAs gives investors an institutionalized diplomatic channel to resolve taxation not in accordance with the treaty, shielding them from arbitrary domestic assessments or protracted litigation.
C. Combating Double Non-Taxation and Ensuring Transparency
Modern DTAs incorporate robust anti-abuse provisions, including the Principal Purpose Test (PPT) under the OECD/G20 BEPS framework. Investors must recognize that while DTAs exist to facilitate legitimate trade, aggressive tax structures designed solely to exploit treaty networks (treaty shopping) are aggressively dismantled by ZIMRA. Understanding DTAs enables investors to structure legitimate, substance-driven operations that withstand audit scrutiny.
4. Zimbabwe’s DTA Network and Treaty Rates: Fees, Remittances, and Royalties
Zimbabwe maintains a comprehensive network of DTAs with major trading and investment partners across Africa, Europe, Asia, and the Middle East. Prominent treaty partners include South Africa, the United Kingdom, Mauritius, Germany, China, Botswana, France, Sweden, the Netherlands, Canada, Poland, Bulgaria, Malaysia, and Kuwait.
To evaluate how these treaties modify domestic law, we must first establish the baseline domestic statutory rates under the Income Tax Act [Chapter 23:06] and Finance Act [Chapter 23:04]:
- Non-Residents’ Tax on Fees (Section 30): Baseline statutory rate of 15% on gross fees for technical, managerial, administrative, or consulting services.
- Non-Residents’ Tax on Remittances (Section 31): Baseline statutory rate of 15% on outward remittances (subject to specific exemptions).
- Non-Residents’ Tax on Royalties (Section 32): Baseline statutory rate of 15% on gross royalties for the use of intellectual property, patents, trademarks, or scientific experience.
When a DTA applies, these baseline rates are frequently modified or capped. Below is a comparative analysis of how specific Zimbabwean DTAs treat these three streams of income.
A. Non-Residents’ Tax on Fees (Technical, Managerial, and Consulting Services)
Under domestic law, Section 30 captures fees paid to non-residents for technical, managerial, administrative, or consulting services at 15%. In DTA terminology, these services are generally dealt with under two distinct articles depending on their duration and structure:
- Article 7 (Business Profits): If a foreign service provider renders consulting services without creating a “Permanent Establishment” (PE)—typically defined as a fixed place of business, branch, office, or a service project exceeding a specific duration threshold (e.g., 6 months)—the business profits are taxable only in the residence state. Thus, ZIMRA is barred from levying the 15% domestic fee tax.
- Article 12 or Specific Technical Fee Protocols: Some DTAs contain explicit clauses capping withholding tax on management and technical fees at rates ranging from 5% to 10%, or allocating exclusive taxing rights to the residence state unless connected to a PE.
- Case Study Analysis — Zimbabwe-South Africa DTA: Under the Zimbabwe-South Africa DTA, income from independent personal services or business profits derived by a South African enterprise is taxable in Zimbabwe only if the enterprise has a Permanent Establishment in Zimbabwe. If a South African engineering firm provides remote consulting advice to a Harare-based mining company from Johannesburg without maintaining a physical office or site exceeding the treaty’s duration threshold, South Africa holds exclusive taxing rights. Consequently, the Zimbabwean company is entitled to apply for a zero-rated tax clearance or exemption, overriding the domestic 15% Section 30 withholding tax, provided valid tax residency certificates (TRCs) are furnished.
B. Non-Residents’ Tax on Remittances (Section 31)
Remittances under Section 31 capture outward transfers of capital, branch profits, and general unilateral payments.
- The Treaty Interaction: DTAs do not contain a standalone “Remittances Article.” Instead, outward remittances are governed by the specific underlying character of the payment (e.g., Dividends under Article 10, Interest under Article 11, Royalties under Article 12, or Business Profits under Article 7).
- Where an outward remittance represents a dividend distribution by a Zimbabwean subsidiary to a foreign parent company, domestic remittance rules interact with DTA dividend caps (typically ranging from 5% to 15%). Where a remittance represents pure commercial payments for imported goods supported by valid bills of entry, domestic law exempts it entirely, rendering DTA invocation unnecessary. However, where remittances represent uncharacterized management fees or branch profit repatriations, ZIMRA scrutinizes the transaction through the lens of the relevant DTA’s business profits or branch tax articles.
C. Non-Residents’ Tax on Royalties (Section 32)
Royalties represent one of the most heavily litigated cross-border income streams. Under domestic law, Section 32 levies a 15% withholding tax on gross royalty payments.
- Treaty Caps: Most of Zimbabwe’s DTAs cap the source-state withholding tax on royalties at rates between 10% and 15%, though certain treaties reduce this further to 5% or 0% for cultural or industrial royalties.
- Empirical Comparison Across Selected Zimbabwean DTAs:
| DTA Partner Country | Domestic Statutory Royalty Rate | DTA Treaty Cap on Royalties | Operational Requirement for Treaty Benefit |
| South Africa | 15% | 10% | Valid South African Tax Residency Certificate (TRC); Beneficial ownership test. |
| United Kingdom | 15% | 10% | TRC issued by HMRC; Non-existence of a Zimbabwean Permanent Establishment. |
| Mauritius | 15% | 15% (Capped at domestic parity in many clauses, but specific limitation of benefits apply) | Substance-over-form test; Mauritian Global Business Licence (GBL) and TRC. |
| China | 15% | 10% | Certificate of Residency from State Taxation Administration of China. |
| Botswana | 15% | 10% | Botswana Unified Revenue Service (BURS) TRC; Arm’s length pricing compliance. |
Analysis of Mauritius DTA: The Zimbabwe-Mauritius DTA has historically been a focal point for international structuring. While Mauritian holding structures were utilized to channel royalties and management fees, modern ZIMRA administrative audits enforce strict substance requirements. Under the Multilateral Instrument (MLI) and domestic anti-avoidance rules, mere incorporation in Mauritius without substantive economic substance, local offices, and qualified personnel will fail the Principal Purpose Test, exposing the remittance to the full 15% domestic royalty tax.
5. Section 4A of the Finance Act and the Currency Imperative in DTA Application
Navigating DTAs in Zimbabwe cannot be done in isolation from the country’s unique monetary history and current legal framework. Since the re-introduction of multi-currency accounting and subsequent legislative enactments, Section 4A of the Finance Act [Chapter 23:04] has stood as a paramount fiscal gatekeeper.
A. The Principle of Currency Matching in Cross-Border Payments
Section 4A(1)(c) and Section 4A(1)(f) dictate that where taxable income, fees, royalties, or withholding amounts are earned, received, or accrued in foreign currency (such as United States Dollars), the tax must be accounted for, withheld, and remitted in that same foreign currency.
Interaction with DTAs: When a foreign investor invokes a DTA to reduce a withholding tax rate on a royalty payment from 15% to 10%, the reduced percentage is applied directly to the gross foreign currency amount. The resulting tax liability must then be remitted to ZIMRA in foreign currency through authorized banking channels. A taxpayer cannot invoke a DTA to pay withholding tax in local currency (ZiG) if the underlying commercial transaction and royalty accrual were denominated and settled in USD. ZIMRA operational guidelines mandate strict currency matching between the underlying invoice, the DTA relief application, and the final tax remittance.
B. Deeming Provisions and the Burden of Proof
Section 4A(5) grants the Commissioner-General sweeping deeming powers. If ZIMRA audit teams discover that cross-border fee or royalty payments were structured artificially to exploit DTA benefits while concealing domestic source income, or where records have been manipulated to obscure foreign currency receipts, the Commissioner may deem the entire transaction to be a foreign currency amount.
For investors claiming DTA benefits, the legal burden of proof rests squarely on the taxpayer. Under Section 62 of the Income Tax Act, the taxpayer must prove that they are the beneficial owner of the income, that they hold a valid Tax Residency Certificate from the treaty partner state, and that the transaction lacks artificiality.
6. Landmark Judicial Interventions and Tax Administration
The practical application of withholding taxes and DTA benefits in Zimbabwe is continuously tested and shaped by judicial oversight. Superior courts have delivered landmark rulings that define the limits of executive power, tax administration, and treaty enforcement.
A. Executive Overreach and Statutory Validity: M. Mlilo v Minister of Finance (19-HH-605)
In M. Mlilo v Minister of Finance, the High Court confronted executive overreach in fiscal legislation, declaring Statutory Instrument 205/2018 (and associated amendments to withholding mechanisms) ultra vires the enabling statute. The court reaffirmed that substantive taxation law and alterations to tax rates or collection mechanisms must originate strictly from primary parliamentary enactment under the Finance Act, rather than unratified ministerial decrees.
Significance for Investors: Foreign investors and withholding agents must scrutinize ZIMRA administrative notices and circulars against primary legislation and ratified DTAs. Where revenue authorities attempt to override treaty protections via administrative directives without statutory backing, taxpayers possess robust legal grounds for challenge.
B. Separation of Powers: Gonese I v Minister of Finance and Economic Development (22-HH-265)
Reinforcing the doctrine of separation of powers, the court in Gonese scrutinized executive amendments to tax provisions, reaffirming that taxation obligations must be grounded in clear, unambiguous parliamentary statutes.
Significance for Treaty Application: ZIMRA cannot unilaterally disregard a duly gazetted DTA or impose administrative hurdles (such as arbitrary withholding freezes) that contradict the clear wording of an international treaty incorporated under Section 108 of the Income Tax Act.
C. Multi-Currency Enforcement and Corporate Precedents: Unki Mines, Delta Corporation, and Contitouch
In major commercial disputes such as Unki Mines (Pvt) Ltd v ZIMRA & Stanbic Bank (22-HH-729) and Delta Corporation Limited v ZIMRA (24-SC-062), the High Court and Supreme Court addressed multi-currency accounting, tax payment modalities, and statutory interpretation under Section 4A of the Finance Act.
Furthermore, recent rulings such as Contitouch Technologies (Pvt) Ltd v ZIMRA & CBZ (25-HH-057) and Paperhole Investments v Profeeds & ZIMRA (25-HH-063) clarified the mechanics of financial intermediaries and tax remittances under Section 4B of the Finance Act (governing prompt remittances through banking channels within strict 24-hour windows).
Significance for Remittances and Royalties: When multinational corporations remit royalties or technical fees under a DTA, financial intermediaries and withholding agents must ensure immediate crediting to the Consolidated Revenue Fund. Delays expose intermediaries to punitive foreign currency interest rates, emphasizing that administrative precision in executing DTA-relieved payments is just as vital as substantive treaty qualification.
7. Why Investors Must Know DTAs: Strategic Imperatives and Risk Mitigation
Mastering Zimbabwe’s DTA network is not an optional compliance exercise; it is a core commercial necessity for foreign and domestic investors. Failure to understand and operationalize DTAs leads to severe financial and legal exposure.
A. Avoiding Unnecessary Tax Leakages (Cash Flow Optimization)
Without DTA awareness, an investor might blindly absorb the baseline 15% domestic withholding tax on fees, remittances, and royalties. Over a multi-year mining, telecommunications, or technology licensing project involving millions of dollars, overpaying tax by 5% to 15% due to failure to claim treaty benefits represents a catastrophic, unnecessary drain on corporate cash flow. Investors must integrate DTA analysis into their pre-entry financial modeling.
B. Defending Against ZIMRA Audit Adjustments and Penalties
ZIMRA audits frequently target cross-border payments for management fees, technical services, and software royalties. Auditors routinely disallow deductions or demand retroactive withholding tax assessments where foreign entities fail to provide verified Tax Residency Certificates at the time of payment. Knowing the procedural requirements of DTAs ensures that investors maintain contemporaneous documentation, preventing punitive interest and penalty assessments under Section 71 of the Income Tax Act.
C. Navigating the Substance-Over-Form Trap (BEPS and MLI Compliance)
Modern international tax is governed by economic substance. Investors cannot simply establish a shell company in a DTA partner jurisdiction to siphon royalties or management fees into low-tax havens while enjoying Zimbabwean treaty benefits. Under Zimbabwe’s implementation of the Multilateral Instrument (MLI) and the Principal Purpose Test (PPT), ZIMRA actively investigates whether a foreign recipient is the true beneficial owner of the income. Investors must ensure that cross-border structures possess adequate local management, operational assets, and business purpose.
8. Strategic Best Practices for Compliance and Risk Mitigation
To maximize investment returns while maintaining flawless compliance with Zimbabwean tax law and international DTAs, stakeholders should adopt the following strategic roadmap:
- Pre-Transaction DTA Screening: Before executing any cross-border service agreement, licensing pact, or loan agreement, tax counsel must verify whether an operative DTA exists between Zimbabwe and the recipient’s country of residence, identifying exact treaty caps on withholding taxes.
- Mandatory Procurement of Tax Residency Certificates (TRCs): Withholding agents must never apply DTA reduced rates based on mere contractual assertions. A valid, current TRC issued by the competent tax authority of the treaty partner must be obtained and archived prior to disbursing any fee, remittance, or royalty.
- Establishment of Beneficial Ownership: Ensure that the foreign entity receiving the royalty or technical fee has full dominion and control over the funds, rather than acting as a conduit pipe for third-party entities in non-treaty jurisdictions.
- Strict Currency Matching and Banking Compliance: Align all DTA-relieved transactions with Section 4A of the Finance Act. Ensure that foreign currency transactions are settled through authorized dealer banks and that withholding tax returns are filed and paid in the identical foreign currency within statutory deadlines.
- Robust Contractual Structuring: Incorporate clear “gross-up” or tax-apportionment clauses in international contracts, explicitly defining how DTA benefits will be shared or administered between the local payor and the foreign payee.
9. Conclusion
Double Taxation Agreements represent the vital bridge between Zimbabwe’s domestic revenue mobilization objectives and the international capital markets essential for economic growth. By understanding the intricate interplay between the Income Tax Act [Chapter 23:06], the Finance Act [Chapter 23:04], specific treaty caps on fees, remittances, and royalties, and the rigid currency mandates of Section 4A, foreign and domestic investors can protect their capital from confiscatory double taxation.
Compliance in Zimbabwe’s modern fiscal environment requires more than passive adherence to domestic rules; it demands strategic DTA mastery, unwavering economic substance, and rigorous administrative precision. By anchoring cross-border operations in robust legal frameworks and respecting judicial precedents from superior courts, investors can navigate the Zimbabwean regulatory landscape with absolute confidence, ensuring sustainable, profitable commercial engagement.