Bridging the Limpopo: A Plain-Language Guide to the South Africa-Zimbabwe Double Taxation Agreement for Shareholders and Investors
1. Two Nations, One Economic Ecosystem
Cross-border trade and investment between South Africa and Zimbabwe form the lifeblood of regional commerce in Southern Africa. From Johannesburg-listed mining conglomerates with heavy operations on the Zimbabwean Great Dyke to independent South African software developers licensing proprietary code to Harare enterprises, capital flows continuously across the Limpopo River.
However, doing business across borders introduces a formidable fiscal hazard: international double taxation. Imagine a South African tax resident who owns shares in a Zimbabwean operating company. When that Zimbabwean company distributes dividends, the Zimbabwe Revenue Authority (ZIMRA) deducts withholding tax. If the South African Revenue Service (SARS) also taxes that exact same dividend without granting relief, the shareholder faces an unacceptably heavy tax burden—sometimes losing up to half or more of their investment returns purely to tax overlap.
To eliminate this barrier, South Africa and Zimbabwe are bound by a bilateral Double Taxation Agreement (DTA). Far from being an esoteric piece of legal red tape, this treaty acts as a financial shield and navigational map for South African shareholders. This article breaks down the South Africa-Zimbabwe DTA in plain, accessible terms, illustrates how it assists individual and corporate shareholders, examines the exact taxes involved, and reviews pivotal judicial precedents shaping cross-border enforcement.
2. What is a Double Taxation Agreement (DTA) in Plain Terms?
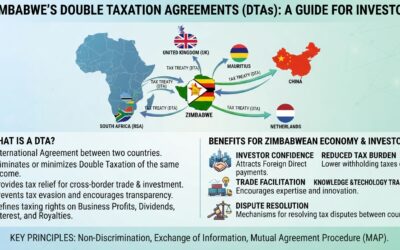
At its core, a Double Taxation Agreement is a formal treaty signed between two sovereign countries to answer one primary question: “Who has the right to tax this money, and how much can they take?”
Without a DTA, both countries might claim full jurisdiction over the same income. A DTA creates a binding set of rules that:
- Splits Taxing Rights: It determines whether the country where the money is made (the source state, such as Zimbabwe) or the country where the investor lives (the residence state, such as South Africa) gets first dibs on taxing the income.
- Caps Withholding Taxes: It places a maximum percentage ceiling on taxes that the source country can deduct when money (such as dividends, interest, or royalties) crosses the border.
- Mandates Relief: It obligates the residence country (South Africa) to give credit for the tax already paid in Zimbabwe, ensuring the investor is never taxed twice on the same dollar.
- Prevents Tax Evasion: It provides mechanisms for tax authorities to share information and resolve disputes without dragging taxpayers through endless legal battles.
3. How the DTA Assists South African Shareholders: Practical Examples
To see the DTA in action, let us look at how it protects South African investors through three common financial scenarios: receiving dividends, earning interest on loans, and collecting royalties on intellectual property.
Example A: The Dividend Dilemma (The Mining Investor)
- The Background: Sipho is a South African tax resident living in Johannesburg who owns a substantial block of shares in a gold-mining subsidiary operating in Bulawayo, Zimbabwe.
- Without the DTA: Under Zimbabwe’s domestic Income Tax Act Chapter 23:06
, dividends paid to a non-resident shareholder attract a hefty withholding tax. Let us assume a domestic baseline rate of 15% to 20%. When Sipho receives his dividend, ZIMRA withholds 20%. When he files his South African tax return with SARS, SARS includes that foreign dividend in his taxable income and might tax it again at his marginal rate (up to 45%), offering no automatic relief. Sipho’s return on investment is decimated.
- With the DTA (Article 10): The South Africa-Zimbabwe DTA steps in and caps Zimbabwe’s right to tax dividends. Under the treaty, if the South African shareholder holds a specific percentage of voting power (often capped at 10% or 15%, or general portfolio holdings), the withholding tax rate is restricted to a maximum of 10% or 15%. Furthermore, when Sipho reports this income in South Africa, SARS grants a foreign tax credit under Section 6quat of the South African Income Tax Act for the tax already paid to ZIMRA. Sipho is taxed fairly, and double taxation is eliminated.
Example B: The Intercompany Loan (The Financial Backer)
- The Background: A Johannesburg-based manufacturing firm extends a commercial loan to its sister company in Harare to upgrade factory assembly lines. The Zimbabwean company pays monthly interest on this loan.
- Without the DTA: ZIMRA classifies cross-border interest payments as subject to non-residents’ tax on interest, often carrying a stiff domestic rate.
- With the DTA (Article 11): The treaty typically caps the withholding tax on interest in the source state (Zimbabwe) at a modest rate (often around 10%). This provides predictability for the South African lender, allowing them to accurately model cash flows and net returns without fearing arbitrary tax spikes.
Example C: Intellectual Property and Software (The Tech Entrepreneur)
- The Background: A Cape Town software company licenses its proprietary inventory-management platform to a major retail chain in Harare. Each month, the retailer remits a royalty fee.
- Without the DTA: ZIMRA’s domestic Non-Residents’ Tax on Royalties (Section 32 of the Income Tax Act) levies a baseline 15% tax on the gross royalty amount.
- With the DTA (Article 12): The treaty restricts Zimbabwe’s royalty withholding tax to a lower ceiling (typically 10%). To claim this reduced rate, the Cape Town software company must provide ZIMRA with a valid Tax Residency Certificate (TRC) issued by SARS, proving it is indeed a tax resident of South Africa and the beneficial owner of the income.
4. The Taxes Involved: Domestic Law vs. Treaty Caps
When analyzing cross-border payments between South Africa and Zimbabwe, investors must understand the dual-layer tax environment:
- The Zimbabwean Domestic Baseline:
- Dividends: Taxed upon outward remittance.
- Interest: Subject to withholding tax under domestic statutes.
- Royalties (Section 32): Baseline rate of 15% on gross intellectual property or software fees.
- Technical and Management Fees (Section 30): Baseline rate of 15% on fees for managerial, consulting, or technical services.
- The DTA Modification: When a South African entity or individual invokes the DTA correctly, these baseline domestic rates are overridden by the treaty caps. However, two critical compliance rules apply:
- The Currency Rule (Section 4A of the Zimbabwean Finance Act): If the underlying commercial transaction is denominated in United States Dollars (USD) or another foreign currency, the withholding tax must be calculated, withheld, and remitted to ZIMRA in that exact same foreign currency. A taxpayer cannot use local currency to settle tax obligations arising from USD transactions.
- The Substance Requirement: Under modern international tax rules (including the Multilateral Instrument or MLI adopted by both nations), shell companies set up purely to exploit treaty rates will fail the Principal Purpose Test (PPT). South African shareholders must prove genuine economic substance and beneficial ownership.
5. Judicial Oversight: Real-World Lessons from Landmark Tax Cases
Cross-border tax administration does not happen in a vacuum; it is heavily policed by the courts. South African investors in Zimbabwe must remain cognizant of key judicial interventions that define how tax laws are interpreted and enforced:
- Executive Overreach and Tax Validity (M. Mlilo v Minister of Finance 19-HH-605): In this landmark case, the Zimbabwean High Court struck down statutory instruments that attempted to alter tax collection mechanisms outside of primary parliamentary enactment. For South African investors, this reinforces a vital principle: ZIMRA administrative directives cannot override primary Acts of Parliament or ratified international treaties. If ZIMRA attempts to impose unauthorized withholding taxes that contradict the South Africa-Zimbabwe DTA, taxpayers have robust legal grounds to challenge the assessment.
- Multi-Currency Enforcement (Unki Mines v ZIMRA 22-HH-729; Delta Corporation v ZIMRA 24-SC-062): These superior court judgments wrestled with the complexities of multi-currency accounting and statutory interpretation under Section 4A of the Finance Act. The courts affirmed that where statutes mandate foreign currency tax compliance, strict adherence is compulsory. For South African parent companies remitting dividends, royalties, or management fees, banking channels and currency matching must be executed flawlessly to avoid punitive foreign currency penalties.
6. Strategic Checklist for South African Shareholders
To successfully navigate the South Africa-Zimbabwe DTA and protect investment returns, shareholders and corporate groups should follow this operational roadmap:
- Obtain a Valid SARS TRC: Never apply for DTA relief based on casual assumptions. Secure an official Tax Residency Certificate from SARS confirming South African tax residency before any payment or dividend distribution occurs.
- Verify Beneficial Ownership: Ensure that the entity receiving the dividend, interest, or royalty is the true economic beneficiary, possessing operational substance rather than acting as a passive conduit.
- Respect Currency Matching: Strictly align all DTA-relieved payments with Section 4A of the Zimbabwean Finance Act—settling USD transactions with USD tax remittances through authorized dealer banks.
- Maintain Contemporaneous Documentation: Archive all withholding tax certificates, board resolutions, and bank remittance slips to withstand ZIMRA audit scrutiny.
7. Conclusion
The South Africa-Zimbabwe Double Taxation Agreement is an indispensable instrument for cross-border investors. By capping withholding taxes on dividends, interest, and royalties, and establishing clear jurisdictional boundaries, the DTA removes the paralyzing threat of double taxation. For South African shareholders, mastering this treaty—while maintaining strict adherence to currency mandates and economic substance—transforms cross-border investing from a fiscal minefield into a predictable, highly profitable enterprise.