Deconstructing Zimbabwe’s Festive Season Liquidity Crunch
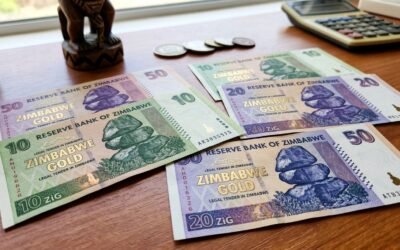
As the festive season approaches, the Zimbabwean economy typically experiences heightened demand for transaction medium—both in local currency (ZiG) and foreign currency (USD). However, periodic liquidity crunches during this peak period present significant operational bottlenecks for businesses and consumers alike.
Analyzing this liquidity squeeze requires evaluating both structural economic mechanisms and intentional macroeconomic policy interventions. The primary drivers behind the constraint can be categorized into four core postulations:
Tight Monetary Policy and Central Bank Liquidity Mopping
The most prominent factor driving the current liquidity constraint is the Reserve Bank of Zimbabwe’s (RBZ) aggressive monetary stance aimed at stabilizing the ZiG and containing inflation.
- Non-Negotiable Certificates of Deposit (NNCDs): The RBZ consistently uses aggressive mopping-up mechanisms—such as non-redeemable, 30-day NNCDs—to siphon excess ZiG liquidity out of the banking system.
- Tight Reserve Money Supply: To protect the exchange rate and anchor single-digit inflation expectations, reserve money growth is strictly capped within Optimal Liquidity Levels (OLL). By restricting commercial banks’ access to local currency reserves, the central bank prevents excess local money from migrating into the parallel foreign exchange market.
- Credit Restraint: High policy rates and strict statutory reserve requirements have curtailed commercial bank lending (leading to a localized “credit crunch”), limiting overall money creation across the broader economy.
Fiscal Discipline and Government Revenue Mopping (QPDs)
Fiscal interventions by the Ministry of Finance, Economic Development, and Investment Promotion play a direct role in mopping up transactional liquidity, particularly toward the end of financial quarters and fiscal years.
- Quarterly Payment Dates (QPDs): Large tax obligations—specifically Corporate Income Tax payable via QPDs—frequently fall in the final quarter. As corporates liquidate local currency holdings and draw on banking deposits to clear tax liabilities, significant liquidity is transferred directly out of circulation and into government coffers at the central bank.
- Controlled Cash Transfers to Government Contractors: Historically, unchecked payments to government contractors and suppliers injected large volumes of local currency into the market, driving parallel rate volatility. The tight coordination between the Treasury’s Cashflow Management Committee and the RBZ now ensures that payments to contractors are strictly staggered, delayed, or paid in non-liquid instruments, reducing market liquidity.
Seasonal Demand Shocks vs Formal Sector Currency Hoarding
The approach of the festive season introduces structural shifts in money velocity and demand, compounding the scarcity of physical and digital cash.
- Increased Demand for Consumer Cash: Year-end bonus payouts, agricultural input purchases (coinciding with the start of the summer cropping season), and festive holiday spending dramatically increase consumer demand for liquid cash (both ZiG cash notes and USD notes).
- Precautionary Hoarding by Businesses: Retailers and importers require higher amounts of hard currency ahead of December to fund holiday stock imports. As businesses hold onto foreign currency reserves and convert local earnings to defend balances against exchange rate movements, circulating liquidity drops sharply.
Institutional Disconnect and Banking Sector Bottlenecks
Even when overall broad money supply appears adequate on balance sheets, structural friction within the financial architecture limits the effective flow of liquidity.
- High USD Mobilization vs. Low ZiG Circulation: A significant portion of bank deposits is denominated in USD. However, these foreign currency deposits are largely locked up in formal banking channels or cautious offshore reserves rather than circulating freely for everyday transactional liquidity.
- Interbank Market Friction: Asymmetries across commercial bank balance sheets mean that while a few large Tier-1 banks may hold liquidity, smaller market players face acute deficits. The interbank lending market often experiences friction due to counterparty risk concerns, preventing efficient liquidity redistribution.
Summary and Outlook
| Postulation | Primary Mechanism | Economic Impact |
| Monetary Stance | RBZ mopping via NNCDs & strict reserve targets | Prevents exchange rate volatility; restricts credit growth |
| Fiscal Policy | QPD tax collections & restricted contractor payouts | Withdraws local currency from commercial bank deposits |
| Seasonal Dynamics | Peak consumer spending & agricultural input demand | Spikes transaction demand faster than money supply expands |
| Banking Structure | USD asset lock-up & interbank market friction | Impairs smooth liquidity circulation across the financial system |
While the liquidity crunch creates short-term friction for business operations, working capital management, and retail trade during a high-demand period, it serves as the deliberate price of price stability—preventing hyperinflationary pressures and keeping the local currency anchored.