Setting Up a Foreign Subsidiary in Zimbabwe: Tax and Regulatory Map
Entering the Zimbabwean market presents compelling commercial opportunities across key sectors such as mining, renewable energy, agriculture, manufacturing., and financial technology. However, navigating the cross-border corporate structure, foreign exchange framework, and tax ecosystem requires a proactive, strategic approach.
Establishing a foreign subsidiary in Zimbabwe requires careful planning regarding corporate tax obligations, foreign exchange controls, profit repatriation channels, and statutory incentives. This comprehensive guide details the key tax and regulatory requirements, strategic considerations, and compliance roadmap for foreign multinational corporations (MNCs) expanding into Zimbabwe.
Choosing the Right Legal Vehicle
When expanding into Zimbabwe, foreign entities primarily choose between two structural options: registering a Branch of a Foreign Company or incorporating a Local Subsidiary Company under the Companies and Other Business Entities Act [Chapter 24:31] (COBE).
| Structural Aspect | Foreign Branch Office | Local Subsidiary (Private Limited Company) |
| Legal Personality | Extension of the parent company; full legal exposure to parent. | Separate legal entity; limited liability protection for the parent company. |
| Corporate Income Tax (CIT) | Standard rate + Branch Profits Tax considerations. | Standard Corporate Income Tax rate applies. |
| Withholding Taxes (WHT) | Branch remitting profits to HQ may face Branch Profits Tax (subject to DTTs). | Dividends distributed to foreign parents are subject to Non-Resident Shareholders’ Tax (NRST). |
| Local Investment Approval | Often subject to stricter scrutiny by regulatory authorities. | Preferred structure for local licencing, joint ventures, and government tendering. |
Strategic Recommendation: For long-term operations, establishing a local subsidiary is generally preferred. It insulates the parent company from direct liability and provides access to local tax incentives, double taxation treaties, and clearer avenues for profit repatriation.
Mandatory Regulatory Setup and Registration Roadmap
To operate lawfully and qualify for tax treaty benefits, a foreign subsidiary must complete a sequential registration process across key government regulatory bodies:
[1. ZIDA License] ➔ [2. Company Incorporation (COBE)] ➔ [3. ZIMRA Tax Registration (TIN/TaRMS)] ➔ [4. RBZ Exchange Control Approval]
Zimbabwe Investment and Development Agency (ZIDA) License
Foreign investors should apply for a ZIDA Investment License. While not strictly mandatory for every sector, a ZIDA license provides essential protections under the ZIDA Act [Chapter 14:37], including:
- Protections against expropriation.
- Guarantees for foreign capital repatriation.
- Access to investor facilitation services and streamlined work permit processing.
Company Incorporation via COBE
Registering a local subsidiary involves filing the Articles and Memorandum of Association, appointing a local resident public officer/director, and obtaining a Certificate of Incorporation from the Companies Registry.
ZIMRA Registration (TIN and TaRMS Portal)
Once incorporated, the company must register with the Zimbabwe Revenue Authority (ZIMRA) to obtain a Tax Identity Number (TIN) and set up its profile on the Tax Administration and Revenue Management System (TaRMS).
Reserve Bank of Zimbabwe (RBZ) Exchange Control Approval
All foreign capital injections, intercompany loan agreements, and technology transfer agreements must be registered with the Reserve Bank of Zimbabwe Exchange Control Division through an Authorised Dealer (commercial bank).
Core Corporate Tax Landscape for Foreign Subsidiaries
Understanding the key primary taxes applicable to corporate entities in Zimbabwe is vital for financial forecasting and compliance planning.
Corporate Tax Framework Summary:
├── Corporate Income Tax (CIT)  ➔  Standard Base Rate + AIDS Levy
├── Value Added Tax (VAT)       ➔  Standard Rate on Eligible Goods & Services
├── Withholding Taxes (WHT)     ➔  NRST on Dividends, Royalties, & Management Fees
└── Intermediated Money Tax     ➔  IMTT on Digital & Electronic Transfers
Corporate Income Tax (CIT)
- Standard Rate: Corporate Income Tax is levied on taxable income derived from sources within or deemed to be within Zimbabwe (currently at 25%).
- AIDS Levy: A statutory 3% levy is assessed on the tax calculated, bringing the effective corporate tax rate to the prevailing standard threshold.
- Payment Terms: Tax is paid via Quarterly Payment Dates (QPDs) throughout the tax year based on estimated annual income.
Value Added Tax (VAT)
- Registered operators making taxable supplies must register for VAT if they meet the statutory annual turnover threshold.
- Subsidiaries supplying imported services must account for reverse-charge VAT on imported services where applicable.
- Levied at a standard rate of 15.5%
Intermediated Money Transfer Tax (IMTT)
- IMTT is levied on electronic transactions across bank transfers and mobile payment platforms.
- Planning Note: Business-to-business transactions and specific capital transfers carry statutory exemptions or capped thresholds. Reviewing transaction structures minimizes unnecessary IMTT exposure.
International Tax Strategy: Cross-Border Transactions and Profit Extraction
For a foreign parent company, structuring cross-border cash flows efficiently is critical to avoiding double taxation and unexpected tax leakages.
Non-Resident Shareholders’ Tax (NRST) on Dividends
When the subsidiary declares and distributes dividends to its foreign parent, it must withhold Non-Resident Shareholders’ Tax (NRST). Standard statutory rates apply unless reduced under a Double Taxation Agreement (DTA).
Double Taxation Agreements (DTAs)
Zimbabwe has active Double Taxation Agreements with several jurisdictions (including South Africa, the United Kingdom, Mauritius, Botswana, the UAE, and China). Strategically holding or structuring parent ownership via a DTA jurisdiction can significantly reduce withholding tax rates on:
- Dividends (NRST)
- Royalties (NRTR)
- Management & Technical Fees (NRMF)
- Cross-Border Interest Payments
Transfer Pricing Compliance (Section 98A of the Income Tax Act)
Transactions between the local subsidiary and its foreign parent or group affiliates (e.g., management fees, cross-border loans, intellectual property licensing, raw material sales) must be conducted at arm’s length.
- Documentation Requirement: Zimbabwe enforces strict Transfer Pricing regulations based on OECD guidelines. Contemporaneous transfer pricing documentation must be maintained and submitted upon request by ZIMRA.
- Penalties: Non-compliance or unsupportable transfer pricing methods incur significant non-deductibility penalties and statutory interest.
Thin Capitalization Rules
Intercompany loans supplied by foreign parents to local subsidiaries are subject to thin capitalization restrictions:
- Debt-to-Equity Thresholds: Excess debt funding exceeding statutory debt-to-equity ratios may result in the disallowance of interest deductions on the surplus debt.
- Exchange Control Approval: Foreign shareholder loans must receive prior Exchange Control approval from the RBZ to guarantee deductible status and enable interest/principal repayments abroad.
Strategic Incentives and Special Economic Zones (SEZs)
Foreign investors can lower their effective tax burden by leveraging targeted legislative incentives:
- Special Economic Zones (SEZs): Investing in designated SEZs or licensed SEZ projects offers major fiscal benefits, including:
- Corporate Income Tax holiday (0% for the initial period, followed by reduced corporate rates).
- Duty-free importation of capital equipment and raw materials.
- Exemption from Non-Residents’ Tax on fees and dividends.
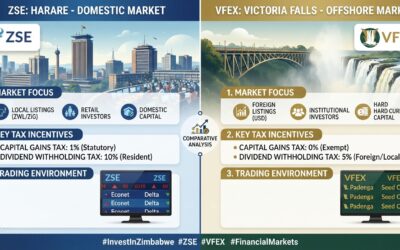
- Victoria Falls Stock Exchange (VFEX) Tax Exemptions: Capital gains realized on securities listed on the VFEX are exempt from Capital Gains Tax, and reduced dividend withholding tax rates apply to foreign investors.
- Capital Allowances: Accelerated depreciation allowances (Special Initial Allowance) are available on qualifying capital expenditure for industrial buildings, plant, and machinery.
Local Employer and Payroll Tax Compliance
A foreign subsidiary employing local or expatriate personnel must integrate the following payroll taxes into its operational workflow:
- Pay As You Earn (PAYE): Deducted monthly from employee remuneration using prescribed tax bands (accounting for foreign currency and local currency salary structures).
- National Social Security Authority (NSSA): Mandatory pension contributions split equally between employer and employee.
- Standards Development Fund (SDF) & ZDEFLEX: Statutory levies calculated as a percentage of total gross payroll.
Strategic Checklist
When planning the deployment of a foreign subsidiary in Zimbabwe, complete this actionable pre-launch checklist:
- Structural Selection: Decide between a branch or local subsidiary based on liability and DTA tax benefits.
- ZIDA Licensing: Obtain investment licenses to secure capital guarantee rights.
- Exchange Control Registration: Formally register all shareholder equity injections, technology agreements, and foreign debt structures with the RBZ via an Authorised Dealer.
- Transfer Pricing Policy: Prepare contemporaneous transfer pricing documentation for all intercompany services, royalties, and inventory transactions.
- Tax Portal Setup: Finalize ZIMRA BP registration and set up TaRMS administrative access prior to commercial launching.
- Fiscalisation Compliance: Install approved Fiscalised Electronic Register/FDMS integration for automated invoice reporting.
Conclusion
Establishing a foreign subsidiary in Zimbabwe requires balancing regulatory compliance with strategic international tax planning. By aligning your corporate entry strategy with ZIDA protections, leveraging Double Taxation Treaties, enforcing transfer pricing policies, and securing Reserve Bank Exchange Control approvals early, foreign multinational corporations can build an operational footprint optimized for long-term profit repatriation and risk management.
Disclaimer: This article is intended for general information purposes and does not constitute formal tax, legal, or financial advice. Investors are advised to consult certified tax practitioners and legal counsel in Zimbabwe prior to executing cross-border transactions.