Tax Compliance Advisory
Navigating ZIMRA’s Automated Era (TaRMS & FDMS)
A Dive
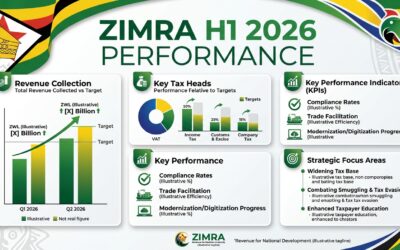
The Zimbabwe Revenue Authority (ZIMRA) H1 2026 performance highlights demonstrate a fundamental shift in tax administration. Collecting USD 4.71 billion ($16.14\%$ above target and $+46.73\%$ year-on-year), ZIMRA’s revenue growth was driven by three primary levers: Visibility (TaRMS & FDMS integration), Execution, and Aggressive Debt Control.
With 100% FDMS-TaRMS integration and all 16 commercial banks connected directly to the system, the tax authority now possesses near-instantaneous visibility across all commercial transactions. Discrepancies between bank inflows, fiscalized invoice data, customs declarations, and tax returns are no longer manually discovered during routine checks—they are automatically flagged by TaRMS algorithms in real time.
To avoid severe penalties, interest, asset seizures, or business disruption, enterprises must align their internal processes with ZIMRA’s digital surveillance ecosystem.
Key Takeaways from ZIMRA’s H1 2026 Performance
| Metric / Highlight | Data Point | Compliance Implication for Businesses |
| Net USD Revenue Collected | USD 4.71 Billion (+16.14% vs target) | Driven by high audit yield, strict enforcement, and automated intelligence. |
| TaRMS & FDMS Integration | TaRMS: 98% | FDMS: 99% |
| Banking Integration | 16/16 Banks Integrated | Bank settlement data is cross-referenced with reported revenue instantly. |
| Fiscal Invoices Processed | 20.4 Million Invoices | Unregistered or off-book sales are easily detected through gaps in sequential or volume data. |
| Cargo & Border Enforcement | 73,085 Cargo Scans | 1,480 Notices of Seizure | High focus on Post-Clearance Audits (PCA), undervaluation, and transit fraud. |
| National Filing Compliance | LCO: ~98% | MCO: ~92% | Baseline compliance is high; non-filers and delayed filers instantly stand out as high-risk targets. |
| Cumulative USD Tax Debt | USD 1.26 Billion | ZIMRA is actively enforcing collection, garnish orders, and debt recovery. |
The New Reality: How TaRMS Auto-Flags Discrepancies
TaRMS (Tax and Revenue Management System) functions as a central data hub, pulling real-time information from multiple external and internal touchpoints:
- Banking & Financial Data (All 16 Commercial Banks):
- The Trap: Declaring $100,000 USD in gross revenue while bank inflows total $300,000 USD across foreign currency accounts (FCA) and local accounts.
- The Outcome: Automated discrepancy alerts trigger immediate tax assessments, garnishee orders, and 100% principal penalties.
- FDMS (Fiscalisation Data Management System):
- The Trap: Operating without fiscal devices, issuing non-fiscalized manual invoices, or failing to report virtual invoices.
- The Outcome: B2B buyers lose VAT Input Tax claims on non-fiscalized invoices, leading to supplier disputes, while the seller faces heavy fines per un-fiscalized transaction.
- Customs and Cross-Border Data (ASYCUDA World):
- The Trap: Importing raw materials/goods worth $500,000$ USD at customs, but declaring lower cost of sales or sales figures on local VAT/Income Tax returns.
- The Outcome: Post-Clearance Audits (PCA) reconciliation flags undervaluation, tariff misclassification, or suppressed sales.
- Third-Party / Withholding Tax Cross-Matching:
- The Trap: B2B clients remitting Withholding Tax (10%) against your Tax Clearance Status (ITF263).
- The Outcome: If your client reports payments made to you, but you do not report corresponding revenue in TaRMS, an automated audit notice is issued.
Post-Clearance Audits & Heavy Penalties: The Warning Signs
ZIMRA’s H1 performance highlights 1,480 Notices of Seizure issued and over 73,000 high-risk cargo scans. Post-Clearance Audits (PCAs) are now heavily automated, examining historical customs declarations against internal accounting registers up to 6 years back.
Common Penalty Drivers:
- Off-the-Books Foreign Currency Sales: Failing to account for multi-currency transactions proportionally in PAYE, VAT, and Corporate Income Tax.
- Misclassification & Undervaluation at Ports: Improper HS code assignment or lower invoiced values to reduce Customs Duty.
- Delayed VAT / PAYE Submissions: Penalty rates compounded daily, accompanied by high interest charges.
Operational Survival Guide: What Businesses Must Do
To remain compliant, viable, and operational in an automated tax environment, businesses should adopt the following measures:
Implement Monthly “3-Way Reconciliations”
Before submitting monthly VAT, PAYE, or quarterly QPD (Corporate Income Tax) returns, perform internal 3-way reconciliations:
Bank Settlements (All Currencies)——— >FDMS Invoiced Totals———–>TaRMS Declaration
- Any variance between bank credits, point-of-sale data, and declared income must be documented with clear accounting justifications (e.g., inter-account transfers, loan disbursements, capital injections).
Full Virtual/Hardware Fiscalisation Compliance
- Ensure 100% of sales channels (POS, e-commerce, ERP, manual billing) are fully integrated into FDMS.
- Regularly verify that invoice QR codes, ZIMRA signatures, and verification links generate valid records on the ZIMRA portal.
Align Customs Declarations with Accounting Books
- Standardize inventory management to map ASYCUDA Customs declarations directly to inventory control accounts.
- Ensure import valuations match transfer pricing rules and bank payment records (Form V11 / Form CD1 matching).
- Maintain complete audit trails for high-risk imports to withstand Post-Clearance Audits (PCA).
Audit Multi-Currency Payroll (PAYE Precision)
- Ensure PAYE is accurately calculated and remitted in the exact currency mix in which remuneration was earned (e.g., USD portion taxed in USD, local currency portion in ZWG).
- Avoid disguised allowances or non-taxed perks that trigger back-dated PAYE assessments during ZIMRA payroll audits.
Regular Tax Health Checks and Voluntary Disclosures
- Conduct quarterly internal or external tax audits to identify discrepancies before ZIMRA’s automated scripts flag them.
- If errors are discovered internally, utilize ZIMRA’s Voluntary Disclosure Program to rectify omissions prior to audit notification. Voluntary disclosures significantly mitigate or eliminate penalties.
Checklist
- Bank Reconciliation: Are all bank accounts (USD & ZWG) reconciled against tax returns monthly?
- Fiscalisation Status: Is your FDMS onboarding at 100%, with all sales issued with ZIMRA fiscal receipts?
- Customs Records: Are import documents (Bills of Entry, invoices, duty receipts) kept systematically for 6+ years for PCA readiness?
- Tax Clearance (ITF263): Is your tax account in good standing to avoid the automatic 10% withholding tax deduction by clients?
- Debt Settlement: If carrying tax arrears, have you negotiated an official ZIMRA payment plan to avoid bank garnishee orders?