Taxation of Wholesale and Retail Trade, Repair of Motor Vehicles and Motorcycles business in Zimbabwe.
Industry Overview
The Wholesale and Retail Trade sector (alongside motor vehicle and motorcycle repairs) is a cornerstone of Zimbabwe’s domestic economy, heavily influenced by cash transactions, formal and informal supply chains, and extensive import-export activities. Operating within this sector requires stringent adherence to ZIMRA’s tax administration framework, consumer protection laws, and local municipal bylaws.
This analysis examines the primary tax heads, compliance red flags, landmark tax court cases, critical investor considerations, and available tax incentives applicable to businesses in this sector.
Main Tax Heads in the Sector
Businesses operating in the wholesale and retail trade, or motor vehicle/motorcycle repair sectors, are typically liable to the following primary tax heads administered by ZIMRA via the TaRMS platform:
- Corporate Income Tax (CIT):
- Scope: Levied on taxable income derived from trading profits, commercial rentals, and asset disposals.
- Rate: Standard corporate income tax applies (currently 25% plus AIDS levy of 3%, effective 25.75%).
- Value Added Tax (VAT):
- Scope: Mandatory registration threshold applies. Retailers and wholesalers collect VAT on standard-rated sales of goods and services (e.g., clothing, hardware, motor vehicle spare parts, repair services). Certain basic commodities may be zero-rated or exempt.
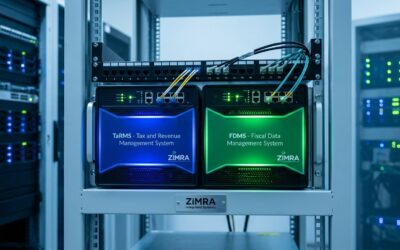
- Compliance: Must be integrated with ZIMRA’s Fiscal Device Management System (FDMS) for real-time sales reporting.
- Pay As You Earn (PAYE):
- Scope: Monthly payroll tax deducted from employees’ emoluments (salaries, wages, allowances) and remitted to ZIMRA.
- Intermediated Money Transfer Tax (IMTT):
- Scope: Levied on electronic money transfers, bank transactions, and mobile money payments across business accounts.
- Withholding Taxes (WHT):
- Scope: Deducted at source on payments made to resident and non-resident contractors, suppliers, management fees, and commercial rentals.
- Plastic Packaging Tax (Plastic Tax):
- Scope: A specific environmental levy imposed on retail plastic carrier bags provided to customers at checkout.
- Customs & Excise Duty:
- Scope: Critical for wholesalers and retailers importing goods for resale, or motor vehicle repair shops importing spare parts and accessories.
Compliance Red Flags & Audit Triggers
ZIMRA and regulatory bodies closely monitor the retail and wholesale sector due to high cash turnover and supply chain complexities. Key red flags include:
- Non-Fiscalisation or Sales Suppression: Operating Point of Sale (POS) terminals or cash registers not linked to ZIMRA’s FDMS, or issuing manual/undercounter receipts.
- VAT Input vs. Output Mismatches: Claiming input VAT on private expenses, unverified invoices, or suppliers who are not tax-compliant (not registered or lacking valid Tax Clearance Certificates).
- Undeclared Foreign Currency Revenue (USD): Failing to accurately account for multi-currency transactions, particularly cash USD sales versus bank deposits.
- Payroll Discrepancies: Discrepancies between declared PAYE figures and NSSA/NEC employee schedules, or failure to register part-time/casual retail staff.
- Transfer Pricing in Retail Chains: Undervaluation or overvaluation of goods transferred between related group entities (wholesalers to retail subsidiaries).
Landmark Court Cases and Legal Precedents
Tax disputes in Zimbabwe’s commercial and retail sectors frequently center around VAT classifications, fiscalisation penalties, and the valuation of imported goods. Notable legal themes and principles established through the Fiscal Appeal Court and Supreme Court include:
- Burden of Proof in Tax Assessments: Zimbabwean courts consistently uphold that under the Revenue Authority Act and Tax Acts, the burden of proof rests heavily on the taxpayer to disprove ZIMRA’s estimated assessments by producing verifiable books of accounts, till tapes, and bank records.
- Fiscalisation Enforcement: Cases involving non-compliance with electronic fiscal device regulations have reinforced ZIMRA’s powers to levy severe penalties and seize unregistered trading equipment.
- VAT Zero-Rating and Export Proof: Retailers claiming zero-rating on cross-border sales or supplies to diplomats must maintain absolute documentary proof (customs bills of entry, export permits); failure to do so results in retrospective standard-rating assessments plus punitive interest.
What Investors and Businesses Need to Know
For foreign and local investors entering the wholesale, retail, or motor vehicle repair trade in Zimbabwe, practical success requires navigating several operational realities:
- Foreign Participation & Retail Quotas: Ensure compliance with national investment laws, local equity thresholds (where applicable), and ZIDA licensing conditions.
- ZIDA & Municipal Licenses: In addition to company incorporation, businesses must secure ZIDA licenses, municipal shop licenses, health department approvals, and fire safety clearances before opening doors.
- Real-Time Tax Integration: Systems architecture must incorporate ZIMRA-certified fiscal memory devices from day one of trading. Retrofitting POS systems post-launch frequently causes severe operational downtime and penalties.
- Supply Chain Documentation: Complete customs clearing documentation must be maintained for all imported stock to prevent seizure during ZIMRA unannounced inspections.
Tax Incentives Available in the Sector
While standard retail trading rarely attracts aggressive tax holidays compared to export manufacturing or mining, certain incentives and structuring options exist:
- Special Economic Zones (SEZs) / ZIDA Designated Projects: Retail or wholesale operations established within gazetted industrial parks or designated priority investment areas may qualify for preferential corporate tax rates (e.g., 0% for the first 5 years and 15% thereafter) and duty-free importation of capital equipment.
- Rebate of Duty on Capital Equipment: Importers of qualifying industrial machinery and heavy commercial repair equipment may apply for duty rebates under specific statutory instruments to encourage capital investment.
- Training and Employment Tax Credits: Incentives linked to apprenticeship programs or employment creation in designated sectors.